

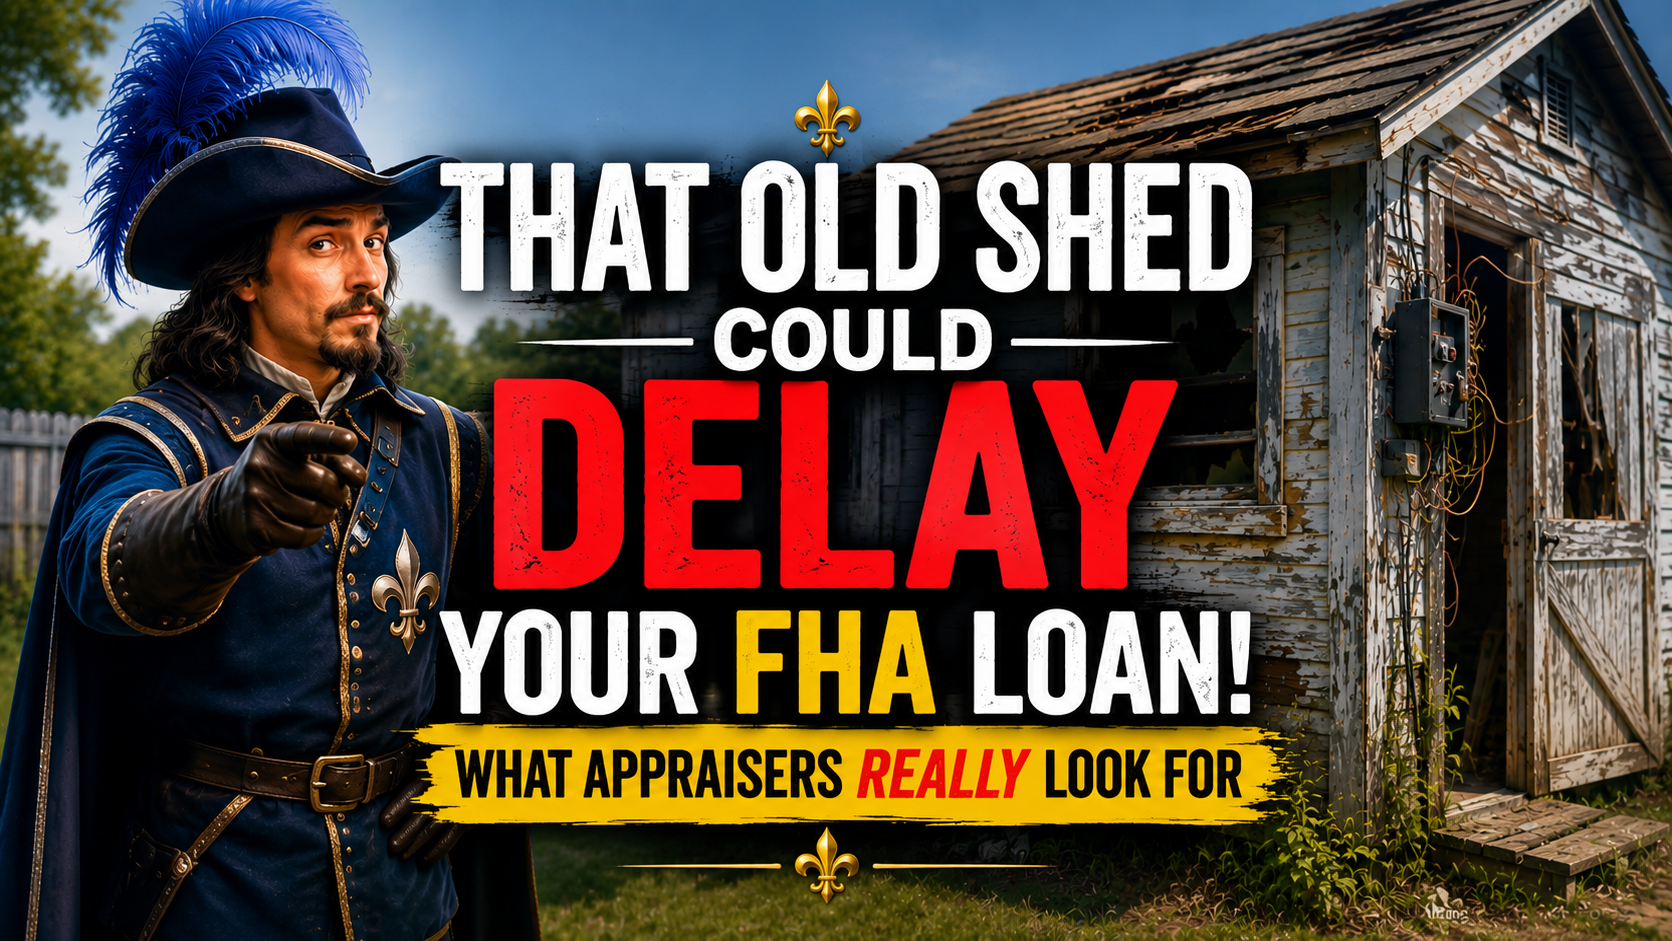
FHA Appraisal Outbuilding Guidelines: What Appraisers Look For in Sheds and Garages

The Backyard Blindspot: How an Old Shed Can Delay Your FHA Closing
Most buyers and sellers spend days preparing the house for an FHA appraisal. They clean every room, touch up paint, mow the lawn, and make sure the home is ready for the appraiser.
Then the appraiser walks into the backyard.
That’s where I see many FHA appraisal problems begin.
The old detached garage. The workshop that’s been used for storage for twenty years. The backyard shed that everyone stopped noticing years ago because “it’s just a shed.”
Those forgotten outbuildings are often what turn an otherwise clean FHA appraisal into one that’s Subject to Completion.
In my experience, the biggest culprit isn’t a catastrophic structural failure. It’s usually deferred maintenance. Peeling paint that should have been addressed years ago. Broken windows. Exposed wiring. A leaking roof. Rotten steps. Individually, these are often inexpensive repairs. Together, they can delay your closing, require a completion inspection (1004D), and cost additional money that nobody planned to spend.
The frustrating part is that most of these issues are completely avoidable.
The purpose of this guide isn’t to convince you that every old shed needs to be replaced. It’s to show you exactly what FHA appraisers look for so you can identify the obvious issues before the appraisal—not after you’ve received a repair list and your closing has been pushed back.
Sometimes FHA appraisal problems don’t start in the house. They start in the backyard.
Does FHA Require Detached Garages and Sheds to Meet Minimum Property Standards?
Yes. If a detached garage, workshop, pole barn, storage shed, carport, or other outbuilding is part of the real property being financed, it is included in the FHA appraisal. While these structures don’t have to be new or cosmetically perfect, they must meet FHA’s Minimum Property Standards for safety, security, and structural soundness.
That doesn’t mean every scratch, dent, or weathered board will cause problems. FHA appraisers aren’t looking for perfection—they’re evaluating whether an outbuilding presents a health or safety risk, contains significant structural deficiencies, or has deteriorated to the point that it affects the property’s marketability or livability.
When evaluating detached structures, FHA appraisers generally focus on three fundamental questions:
- Is it safe? Are there exposed electrical hazards, unstable stairs, collapsing floors, or other conditions that could injure someone?
- Is it structurally sound? Does the building have a stable foundation, intact framing, and a roof capable of protecting the structure from the elements?
- Is it secure? Can the building be reasonably secured against weather intrusion and unauthorized entry, or has it deteriorated into an abandoned or hazardous condition?
The same principles apply whether the structure is a detached garage, workshop, storage shed, pole barn, or traditional barn. FHA doesn’t maintain a separate set of rules for each type of outbuilding. Instead, the appraiser applies the same Minimum Property Standards used throughout the property and determines whether the structure contributes to—or detracts from—the property’s overall safety and condition.
The key takeaway is simple: an outbuilding doesn’t have to look beautiful to pass an FHA appraisal. It simply needs to be safe, structurally sound, and free of conditions that would create a legitimate concern for the property’s occupants or the lender.
What Do FHA Appraisers Look For in Detached Structures?
Once an FHA appraiser determines that a detached garage, workshop, barn, or storage shed is part of the property, the next step is evaluating its overall condition. The goal isn’t to determine whether the structure is attractive or modern. Instead, the appraiser is looking for conditions that could affect the property’s safety, security, or structural soundness.
Below are some of the most common issues FHA appraisers evaluate when inspecting detached structures.
Structural Integrity
One of the first things an appraiser notices is whether the building appears structurally stable. A detached structure that has stood for decades without significant deterioration is rarely a concern simply because it’s old. However, visible signs of structural failure can quickly become an appraisal issue.
Common structural concerns include:
- Leaning or bowing walls
- A roof that is sagging or beginning to collapse
- Broken or deteriorated framing members
- Severe wood rot that compromises the building’s strength
- Foundation movement or settling that threatens the structure’s stability
Minor cosmetic wear from age is generally not a problem. What matters is whether the structure still performs its intended purpose safely. An old storage shed with weathered siding may be perfectly acceptable, while a newer shed with collapsing walls or a failing roof may require repairs before the loan can close.
Ultimately, the appraiser is asking one simple question:
“Is this structure stable enough to remain on the property without creating a safety hazard?”
If the answer is yes, the structure will often move on to the next phase of the appraisal. If the answer is no, repairs—or in some cases removal—may be required before the FHA loan can be approved.
Peeling Paint
If I had to pick one detached structure issue that causes more FHA appraisal headaches than almost any other, it would be peeling paint.
Detached garages, storage sheds, barns, and workshops are often the last structures homeowners think about maintaining. They may have gone years without being painted, leaving siding, trim, doors, and window frames with flaking or exposed wood. Because these buildings sit in the backyard, many sellers don’t even notice the deterioration until the appraiser points it out.
Unfortunately, FHA appraisers do notice.
Peeling paint is one of those conditions that frequently turns an otherwise clean appraisal into one that’s subject to completion. That means the deteriorated paint must be repaired before the loan can close, followed by a return inspection to verify the work was completed. The result is often additional appraisal fees, unnecessary delays, and frustration for everyone involved.
During the appraisal, expect the appraiser to look closely at painted surfaces on detached structures, including:
- Garage doors and trim
- Wood siding
- Fascia and soffits
- Window and door frames
- Exterior doors
- Barns, workshops, and storage sheds
The easiest way to avoid this problem is to inspect your outbuildings before the appraisal. If you see paint that’s peeling, flaking, blistering, or exposing bare wood, it’s worth addressing before the appraiser arrives. A relatively inexpensive paint project completed ahead of time can eliminate one of the most common repair conditions I see on FHA loans.
While older homes may receive additional scrutiny because of the possibility of lead-based paint, the bigger takeaway for buyers and sellers is simple: don’t ignore peeling paint on detached structures. It’s one of the easiest issues to prevent—and one of the most common reasons an FHA appraisal is delayed.
Roof Condition
The roof is one of the first things an FHA appraiser notices on any detached structure because it provides an immediate indication of whether the building has been maintained. A weathered roof doesn’t automatically create an appraisal issue, but one that has deteriorated to the point where it no longer protects the structure can.
Common roof conditions that may require repairs include:
- Missing or damaged roofing materials that expose the structure to the elements
- Active leaks or obvious signs of ongoing water intrusion
- A sagging roofline that suggests structural failure
- Large holes or sections that have collapsed
- Severe deterioration that threatens the building’s stability
A leaking roof often creates additional concerns beyond the roof itself. Water intrusion can lead to rotted framing, weakened flooring, mold growth, or electrical hazards inside the outbuilding. By the time an appraiser notices a failing roof, there may already be multiple conditions that need to be addressed.
On the other hand, an older roof that still protects the structure and shows no signs of failure may not require any repairs at all. FHA appraisers aren’t trying to determine how many years of life remain on a detached garage or shed roof. They’re evaluating whether the roof is performing its basic function—keeping the structure safe, dry, and structurally sound.
When walking around your property before the appraisal, look for missing shingles or metal panels, obvious sagging, daylight visible through the roof, or evidence of long-term water damage. Addressing these issues before the appraisal can help prevent the report from being made subject to completion, saving both time and the cost of a return inspection.
Electrical Hazards
Electrical problems are among the most common reasons an FHA appraiser calls for repairs on a detached garage or storage shed. While appraisers aren’t licensed electricians and don’t perform electrical inspections, they are required to identify readily observable safety hazards. If exposed wiring or other dangerous electrical conditions are visible, they will often note them in the appraisal report.
Some of the most common electrical issues include:
- Exposed wiring inside or outside the structure
- Hanging or loosely supported electrical cables
- Extension cords being used as permanent wiring
- Open or uncovered electrical panels
- Missing outlet or switch covers
- Damaged light fixtures or exposed electrical connections
- Evidence of electrical arcing, burning, or overheating
One of the questions homeowners often ask is, “Will exposed wiring in a backyard shed affect my FHA appraisal?” The answer is it certainly can. If the wiring presents an obvious shock or fire hazard, the appraiser may require the condition to be corrected before the loan can close.
Keep in mind that the appraiser isn’t evaluating whether the electrical system meets every local building code. Instead, they’re asking a much simpler question:
Does this electrical condition present an obvious safety risk to the occupants or the property?
If the answer is yes, the appraisal may be completed subject to repairs, requiring the hazard to be corrected and verified through a completion inspection before closing.
Before your FHA appraisal, take a few minutes to inspect every detached structure for exposed wiring, loose electrical boxes, open panels, broken fixtures, or extension cords being used as permanent power sources. Correcting these obvious hazards beforehand is often inexpensive and can help prevent unnecessary delays and additional appraisal fees.
Trip and Safety Hazards
Not every FHA appraisal repair involves a major structural problem. In many cases, it’s the simple safety hazards around a detached structure that create the issue.
Remember, FHA appraisers aren’t trying to determine whether a property is perfect—they’re looking for conditions that could reasonably cause someone to get hurt. If an obvious trip or fall hazard exists, there’s a good chance it will be noted in the appraisal report.
Some of the most common safety concerns include:
- Rotten or unstable steps leading into a detached garage or shed
- Missing or loose handrails where they’re needed
- Broken or uneven concrete creating trip hazards
- Large holes in walkways or flooring
- Collapsing ramps or platforms
- Rotten deck boards or entry landings
- Flooring inside the structure that feels unsafe or unstable underfoot
Many of these issues develop gradually over time, which makes them easy for homeowners to overlook. You may instinctively step over the broken board or know to avoid the loose step because you’ve lived with it for years. An FHA appraiser, however, sees the property with fresh eyes and asks a simple question:
Could someone reasonably be injured by this condition?
If the answer is yes, the appraiser may require the hazard to be repaired before the loan can close.
The good news is that most trip hazards are inexpensive to fix. Replacing a rotten step, securing a loose handrail, repairing damaged flooring, or leveling an uneven walkway before the appraisal is almost always easier—and less expensive—than paying for a return inspection after the appraisal has already been completed.
A good rule of thumb: If you would warn a guest to “watch your step,” there’s a good chance the appraiser will notice it too.
Broken Windows
Broken windows are one of the easiest FHA appraisal issues to prevent—and one of the easiest to fix.
If a detached garage, workshop, barn, or storage shed has broken, cracked, or missing window glass, replace it before the appraisal. It’s a relatively inexpensive repair that can eliminate a potential appraisal condition and help keep your closing on schedule.
Unlike peeling paint or structural issues, there usually isn’t much to debate. A broken window is a visible defect, and FHA appraisers are expected to report obvious deficiencies they observe during the appraisal.
Before your appraisal, walk around every detached structure and inspect each window. Replace broken panes, repair damaged frames if necessary, and make sure every window is intact. Spending a few dollars on glass now is far less expensive than paying for a return inspection after the appraisal is completed.
Don’t let a $30 window repair become a several-hundred-dollar closing delay.
Will an Old Shed or Detached Garage Fail an FHA Loan?
No. Age alone doesn’t fail an FHA appraisal.
I’ve seen detached garages and storage sheds that were 75 years old pass without issue, and I’ve seen much newer buildings require repairs. The deciding factor isn’t when the structure was built—it’s whether its current condition presents a safety hazard or shows significant deterioration.
An old, weathered workshop that’s structurally sound, has intact windows, a solid roof, and no obvious hazards may pass without a single comment from the appraiser. On the other hand, a newer detached garage with exposed electrical wiring, peeling paint, and broken windows, may receive multiple repair conditions.
The same principle applies regardless of the type of outbuilding. Whether it’s a detached garage, storage shed, pole barn, workshop, or traditional barn, FHA appraisers evaluate the condition of the structure—not its age.
For example, a detached garage might require repairs if it has:
- Peeling exterior paint
- Broken windows
- Exposed electrical wiring
- Rotten steps or unsafe entryways
- A leaking or sagging roof
- Structural deterioration
Likewise, an old backyard shed isn’t likely to become an appraisal issue simply because it’s old. However, if it’s leaning, collapsing, full of exposed hazards, or clearly deteriorating, it can absolutely delay your FHA closing.
The best way to think about it is this:
FHA isn’t trying to eliminate old buildings. It’s trying to eliminate unsafe conditions.
If an outbuilding is safe, structurally sound, and reasonably maintained, its age is rarely the deciding factor. If it has obvious deficiencies that affect safety or habitability, it’s much more likely to receive repair conditions before the loan can close.
Do Outbuildings Need to Be Painted for FHA?
This is one of the most common questions I receive from buyers, sellers, and real estate agents:
“Do I have to paint my detached garage or shed before an FHA appraisal?”
The answer is sometimes—but not simply because it’s faded or ugly.
FHA appraisers aren’t judging how attractive your outbuildings look. They’re evaluating whether deteriorated paint has become a condition that requires repair. When paint is peeling, flaking, blistering, or exposing the underlying surface, it’s one of the most common repair conditions I see on detached garages, sheds, workshops, and barns.
If the paint on an outbuilding is in poor condition, don’t assume the appraiser will overlook it because “it’s just a shed.” Detached structures are part of the real property securing the loan, and they’re evaluated as part of the appraisal.
Before your FHA appraisal, take a few minutes to inspect:
- Detached garages
- Storage sheds
- Workshops
- Barns
- Garage doors
- Trim, fascia, and soffits
- Window and door frames
If you find peeling or deteriorated paint, repainting it before the appraisal is often one of the least expensive ways to avoid a repair condition, a return inspection, and a delayed closing.
The bottom line is simple:
Faded paint rarely matters. Peeling paint often does.
If you’re wondering whether it’s worth spending a Saturday repainting an old shed or detached garage before the appraiser arrives, my advice is simple:
Yes. It’s almost always cheaper than paying for a completion inspection and waiting another week to close.
Can You Tear Down a Shed to Pass an FHA Appraisal?
Yes.
If an old shed is the reason an FHA appraisal is made subject to completion, removing the structure is often an acceptable solution. After all, if the unsafe outbuilding no longer exists, there’s nothing left to repair.
The bigger question isn’t whether you can remove it—it’s whether you should.
That depends on the condition of the building.
For a small storage shed that’s leaning, collapsing, full of peeling paint, or has multiple repair issues, demolition may be the quickest and least expensive option. By the time you repair the roof, replace broken windows, fix exposed wiring, repaint the exterior, and address structural problems, tearing it down may simply make more financial sense.
A detached garage or large workshop is a different story. Because these structures often add utility and value to the property, repairing them is frequently the better investment. While the repairs may cost more upfront, preserving a usable garage is usually preferable to removing it entirely.
Every situation is different, so consider the overall condition of the building before deciding. Ask yourself:
- Is the structure still useful?
- Are the repairs relatively minor?
- Would repairing it cost less than demolition and cleanup?
- Will removing it negatively affect the property’s usefulness or value?
If the answer to those questions points toward demolition, removing the shed before the appraisal may save you time, money, and the hassle of multiple repair conditions.
If the structure has already been called out by the appraiser, remember that the lender and appraiser will typically need to verify that it has been completely removed before the loan can close. That usually means a completion inspection (1004D) to confirm the appraisal condition has been satisfied.
The goal isn’t to save the shed—it’s to eliminate the appraisal issue in the most practical and cost-effective way.
10 Things Sellers Should Check Before the FHA Appraisal
Before the appraiser arrives, spend 15 to 20 minutes walking around your property—especially the detached structures—as if you were seeing them for the first time. Many FHA appraisal repair conditions are obvious once you know what to look for, and addressing them beforehand is almost always easier than delaying your closing and paying for a completion inspection.
As you inspect your detached garage, workshop, barn, or storage shed, ask yourself these questions:
- Is the roof intact? Look for missing shingles or metal panels, sagging areas, holes, or obvious leaks.
- Is there any peeling paint? Walk around every painted surface and look for peeling, flaking, blistering, or exposed wood. This is one of the most common FHA appraisal repair conditions.
- Are all the windows intact? Replace broken or cracked window glass before the appraisal.
- Is any electrical wiring exposed? Look for exposed wires, open electrical panels, broken light fixtures, or extension cords being used as permanent wiring.
- Does the structure appear stable? Check for leaning walls, severe wood rot, broken framing, or signs that the building is beginning to collapse.
- Are there any trip hazards? Repair rotten steps, loose boards, unstable ramps, or damaged flooring that could create a safety hazard.
- Do the doors function properly? Make sure garage and shed doors open, close, and aren’t obviously damaged.
- Has water been getting inside? Look for signs of long-term leaks, rotted flooring, mold, or water damage.
- Is the outbuilding worth repairing? If a small shed has multiple problems, consider whether removing it would be more practical than repairing it.
- Ask yourself one final question: If I were the appraiser, what would catch my attention first? If something immediately stands out as unsafe, neglected, or obviously damaged, it’s probably worth addressing before the appraisal.
Most FHA appraisal issues involving outbuildings aren’t hidden—they’re visible the moment the appraiser walks into the backyard. Spending a little time and money before the appraisal can help you avoid a subject-to-completion appraisal, a return inspection, additional appraisal fees, and a delayed closing.
Frequently Asked Questions
Yes. If a detached garage, workshop, barn, or storage shed is part of the real property being financed, the FHA appraiser will evaluate it as part of the appraisal. The structure doesn’t have to be perfect, but it should be safe, structurally sound, and free of obvious hazards.
Not because it’s old. Age alone isn’t an FHA appraisal issue. What matters is the condition of the structure. An old shed that’s well maintained may pass without issue, while a newer shed with peeling paint, exposed wiring, broken windows, or structural damage may require repairs before closing.
Absolutely. If a detached shed is unsafe, deteriorated, or would cost more to repair than it’s worth, removing it before the appraisal is often the simplest solution. Just make sure it’s completely removed before the appraiser visits the property.
In my experience, peeling paint is the issue I see most often, followed by exposed electrical wiring, roof deterioration, broken windows, and structural problems. Fortunately, these are also some of the easiest issues to identify and repair before the appraisal takes place.
Don't Let the Backyard Delay Your Closing
The biggest FHA appraisal problems don’t always come from the house.
In my experience, they often come from the detached garage, old workshop, or storage shed that everyone forgot about.
I’ve seen buyers, sellers, and Realtors spend weeks preparing a home for an FHA appraisal, only to have the appraisal come back Subject to Completion because of a deteriorated outbuilding sitting in the backyard. Most of the time, it isn’t a major structural failure. It’s peeling paint that should have been scraped and repainted months ago. Or a broken window that costs very little to replace. Or a handful of obvious maintenance items that nobody noticed until the appraiser did.
Those are frustrating repairs—not because they’re difficult, but because they’re usually avoidable.
Before your FHA appraisal, spend a few minutes walking around every detached garage, shed, workshop, or barn. Look at it honestly. If the paint is peeling, the windows are broken, the roof is failing, or there are obvious signs of neglect, address them before the appraiser arrives.
A few hours of maintenance today can prevent a Subject to Completion appraisal, eliminate the cost of a completion inspection, and help keep your closing on schedule.
Have Questions About an FHA Appraisal?
Every property is different. If you’re buying or selling a home with detached outbuildings and you’re unsure whether something is likely to become an FHA appraisal issue, I’d be happy to discuss it with you before the appraisal. Sometimes a quick conversation can save you time, money, and an unnecessary closing delay.
Call us Directly
Text us for a Quick Response