

Why Is My Mortgage Taking So Long? 10 Delays Borrowers Can Prevent
Waiting for your mortgage to close can be frustrating. Every day feels like a week when you’re trying to buy a home, schedule movers, lock in your interest rate, or coordinate a moving date.
The good news is that many mortgage delays are completely preventable. Most aren’t caused by your loan being denied—they’re caused by issues that temporarily pause the process until additional information or documentation is provided.
After helping thousands of homebuyers through the mortgage process, I’ve found that the same borrower-controlled issues delay closings again and again. What’s surprising is that many of these delays happen even after buyers have been warned about them. I’ve learned that knowing what to do and actually doing it aren’t always the same thing. Buying a home is exciting, life gets busy, and it’s easy to underestimate how even a small decision can turn into closing delays. The good news is that these delays are indeed preventable.
Here are 10 common borrower mistakes that can delay your mortgage closing—and what you can do to keep your loan on track.
1. Waiting Days to Sign Loan Disclosures
Mortgage disclosures are one of the easiest things borrowers can control, yet they’re also one of the most common reasons a loan stops moving forward.
Throughout the mortgage process, you’ll receive several sets of disclosures to review and electronically sign. Some are required by federal law, while others are lender-specific or updated because something in your loan changed and has to be redisclosed.
One of the most common responses I hear is, “I’ll sign them tonight,” or “I’ll get to them this weekend.” Unfortunately, that means the loan literally comes to a halt with no progress until you sign.
In many cases, your file can’t move to the next step until those disclosures have been acknowledged. That means underwriting may not review your file, closing documents can’t be prepared, and your loan officer may not be able to order the next step in the process. What feels like a small delay of a day or two can quickly snowball into several days once underwriting turn times are factored in.
Here’s a real-world example:
- Thursday, 10:00 AM: Your loan disclosures are emailed to you for electronic signature.
- Thursday afternoon: You plan to sign them later.
- Friday evening: You finally complete the signatures.
- Saturday & Sunday: Most lenders, underwriters, and title companies aren’t processing loans.
- Monday morning: Your file can finally move to the next step.
What felt like waiting one day actually turned into a four-day delay before your loan could move forward.
Now imagine underwriting is running a 48-hour review queue. Your file doesn’t jump to the front of the line just because you finally signed the disclosures. It joins the queue behind every other file that was submitted before yours. Suddenly, a simple delay in signing disclosures can push your loan back nearly a week!!
The best practice is simple: whenever you receive mortgage disclosures, review them as soon as possible and sign them the same day if everything looks correct. If you have questions, call your loan officer immediately rather than waiting.
Quick Tip: Electronic disclosures typically take less than 10 minutes to review and sign. Those few minutes can keep your mortgage closing on schedule.
2. Waiting Too Long to Send Requested Documents
Why This Causes Delays
One of the fastest ways to slow down a mortgage is waiting to provide documents your loan officer or underwriter has requested.
Mortgage underwriting is essentially a process of verifying information. If an underwriter needs an updated pay stub, a bank statement, an explanation letter, or another supporting document, they can’t finish reviewing your loan until they receive it. Your file simply waits.
What many borrowers don’t realize is that the delay isn’t just the amount of time it takes to send the document. It’s the time it takes to get back into the underwriting review queue.
A Real-World Example
- Tuesday, 9:00 AM: Your loan officer requests an updated bank statement.
- Wednesday: You plan to send it after work.
- Thursday evening: You finally upload the document.
- Friday: It goes into the Underwriting queue to review the file again based on current turn times.
- The FOLLOWING Monday or Tuesday: It is looked at a week later.
Although it only took two days to send the document, your closing timeline may have moved four or five days because your file had to wait for another review.
The same thing happens every day in mortgage lending. Small delays often become much larger delays simply because every review has to wait its turn.
How to Avoid It
The easiest solution is also the simplest: respond as quickly as possible.
If your loan officer requests documentation, try to send it the same day. If you don’t have the document immediately, let your loan officer know when you expect to have it. Good communication allows everyone involved to plan around the delay instead of wondering whether you’re still working on it.
Also, don’t assume a request is optional just because you’ve already submitted similar paperwork. Underwriters frequently need updated documents or additional pages to satisfy lending guidelines.
Quick Tip: Make it a habit to check your email and voicemail several times a day while your mortgage is in process. Responding within hours instead of days is one of the easiest ways to keep your closing on schedule.Tueas
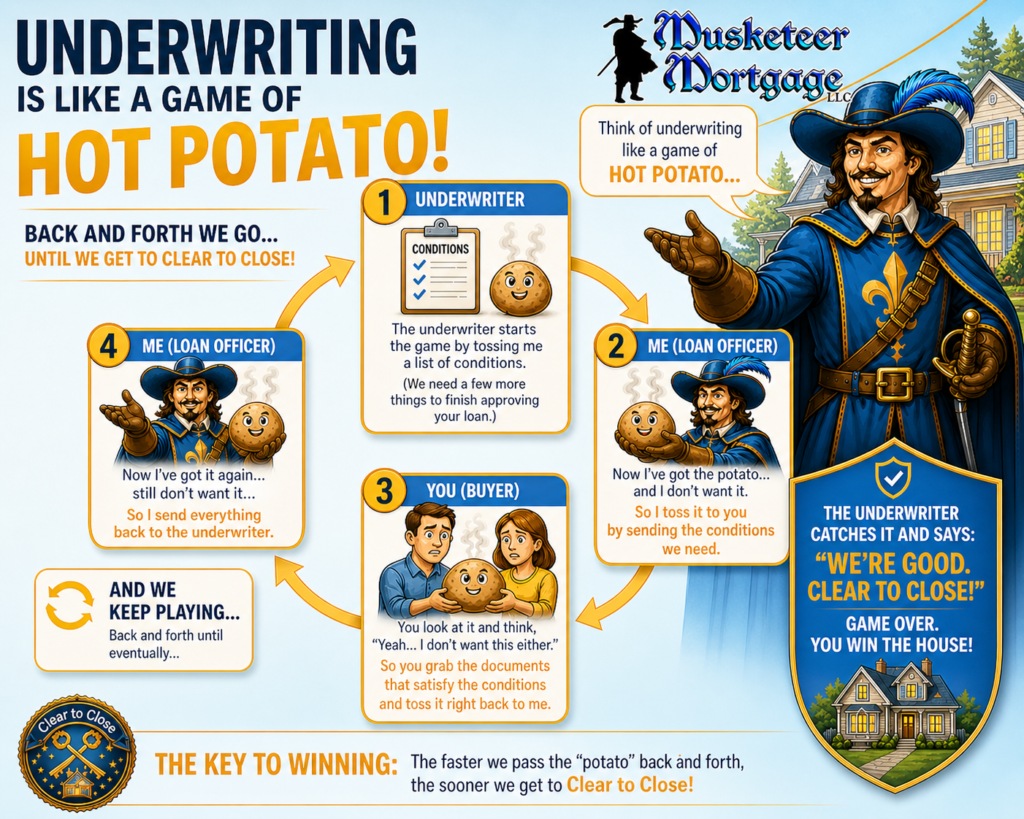
3. Making Large Bank Deposits Without Documentation
One of the quickest ways to create additional underwriting conditions or kill the loan entirely is depositing a large amount of money into your bank account without being able to explain where it came from.
Mortgage lenders are required to verify that the funds being used for your down payment and closing costs come from an acceptable source. When a large, unexplained deposit appears on your bank statement, the underwriter can’t simply assume the money is yours to use. They have to document its source before your loan can move forward.
This doesn’t mean you can’t deposit money during the mortgage process. It simply means you should be prepared to show where it came from.
Common Examples — ***be sure to check with you loan officer BEFORE doing ANY of these things**
These are acceptable sources of funds when they’re documented properly:
- Selling a vehicle
- Receiving a gift from a family member
- Cashing in an investment account
- Receiving a bonus from your employer
- Selling personal property
The key is keeping the paperwork. A bill of sale, gift letter, investment statement, or payroll documentation can usually satisfy the underwriter. However, be sure to check with your loan officer for proper documentation requirements, and to ensure you don’t lose an approval if you decide to use gift funds. They can add layered risk to an approval and must be run through the underwriting system first.
Cash Deposits Are Different
Cash deposits are often the most difficult to document because there may not be a paper trail showing where the money originated.
For example, if you’ve been saving cash at home for years and decide to deposit it into your bank account just before applying for a mortgage, the underwriter generally has no way to verify where those funds came from. Even though the money is legitimately yours, it can create unnecessary questions and delays.
How to Avoid It
If you know you’ll be applying for a mortgage soon, try to avoid making large deposits unless they’re absolutely necessary. If you do receive money from a legitimate source, save every piece of documentation before depositing it.
And if you’re unsure whether a deposit could affect your loan, ask your loan officer before making it. A quick phone call today can prevent several days of underwriting questions later.
Quick Tip: Never assume a large deposit is “too small to matter.” Every lender has different documentation requirements, so it’s always better to ask first than explain it later.
4. Waiting Too Long to Choose Homeowners Insurance
Many buyers are surprised to learn that you can’t close on a mortgage without homeowners insurance. Before your lender can finalize your loan, they must receive proof that the property will be insured beginning on the day you take ownership.
Because insurance is required, waiting until the last few days before closing to shop for a policy can create unnecessary stress—and sometimes unnecessary delays.
Insurance Can Affect More Than Your Premium
Most people know their credit score, but very few realize that insurance companies also use an insurance score when determining eligibility and pricing. This score is different from your mortgage credit score and is based on factors the insurance company believes predict future claims.
Because every borrower has a different insurance score, two people with similar homes can receive very different insurance quotes—or in some cases, one company may decline to insure the property altogether.
If you wait until the week of closing to discover an insurance issue, you may not have enough time to shop other carriers without delaying your loan.
Some Properties Require Extra Time
Certain homes require additional review before an insurance company is willing to issue a policy. For example:
- Properties located in designated flood zones may require flood insurance.
- Older homes may require additional underwriting by the insurance carrier.
- Homes with prior insurance claims or unique characteristics can take longer to insure.
- Some insurance companies may decline coverage, requiring you to find another carrier.
These situations aren’t uncommon, which is why it’s important to start the process early.
Why Your Lender Needs Insurance Early
Your lender doesn’t just need to know you’ve selected an insurance company—they need an insurance binder (sometimes called evidence of insurance) showing the policy, premium, and effective date.
That information is also used to calculate your final debt-to-income ratio (DTI) and complete your Closing Disclosure (CD). Until those numbers are finalized, your lender can’t prepare the documents needed to move your loan toward closing.
Some clients find that because of their insurance score, the specific house itself, or a combination of the two, the cost of insurance might be unreasonably high and can cause the DTI to be too high to keep a loan approval, or it can dramatically impact the cash to close.
For that reason, I recommend choosing your homeowners insurance within the first week after your purchase contract is accepted. That gives everyone enough time to resolve any unexpected issues without putting your closing date at risk.
How to Avoid It
As soon as your offer is accepted, begin shopping for homeowners insurance. Compare rates, ask questions, and work with an agent who can quickly provide an insurance binder once you’ve selected your policy.
If your insurance agent tells you there’s a problem obtaining coverage—or if flood insurance or additional underwriting is required—let your loan officer know immediately. Early communication gives everyone the best chance of keeping your closing on schedule.
Quick Tip: I recommend having your homeowners insurance selected and your insurance binder sent to your lender during the first week of your contract. Waiting until the last few days before closing is one of the easiest ways to create an avoidable delay.
5. Moving Money Between Accounts
This one surprises almost everyone.
Moving money between your own accounts is technically acceptable. There’s no mortgage rule that says you can’t transfer money from checking to savings or from an investment account into your bank account.
The problem isn’t the transfer itself.
The problem is the paper trail it creates.
Every time money moves between accounts, the underwriter has to verify where it came from and where it went. That often means requesting statements or transaction histories from every account involved.
Here’s an Example
Let’s say you move your down payment like this:
Checking Account
⬇️
Savings Account
⬇️
Investment Account
⬇️
Back to Checking
To you, it’s all your money.
To underwriting, it’s now a series of transfers that must be documented.
Instead of reviewing one account, the underwriter may now need:
- Statements from all four accounts
- Transaction histories showing each transfer
- Documentation proving the funds belong to you throughout the process
Why This Becomes So Frustrating
This is one of the most common causes of frustration during underwriting—for borrowers and loan officers alike.
The issue usually isn’t obtaining the bank statement. It’s obtaining the correct documentation.
Every bank and investment company has its own website, mobile app, and online banking system. Some make transaction histories easy to download. Others don’t. Some statements update monthly, while others don’t include recent activity at all.
As a result, borrowers often send screenshots, incomplete records, or statements that don’t show the transfers underwriting needs to see. Then the loan officer has to ask for additional documentation…again.
Screenshots are NEVER acceptable for underwriting. Ever. Never. Ever.
From the borrower’s perspective, it feels like the lender keeps asking for the same thing.
From the lender’s perspective, they’re still waiting for the documentation that satisfies the underwriting requirement.
How to Avoid It
The easiest solution is simple:
Once you’ve started the mortgage process, try to leave your money where it is unless there’s a good reason to move it.
If you do need to transfer funds, tell your loan officer first. They can often advise you on the simplest way to move the money while creating the least amount of additional documentation.
Quick Tip: One transfer usually isn’t a problem. Multiple transfers between multiple accounts can quickly turn into a documentation headache that delays your loan. Think of your bank accounts like evidence in a courtroom. Every transfer creates another link in the chain that has to be proven. The longer the chain, the more documentation underwriting needs before it can approve your loan.
6. Changing Jobs During the Mortgage Process
A common questions I am surprised to receive is:
“Can I change jobs while I’m buying a house?”
The answer is yes…sometimes.
Changing jobs during the mortgage process isn’t automatically a deal breaker; however, it WILL complicate and potentially delay your loan. In many cases, it has little or no impact on your loan approval. But, it almost always means your lender has to take another look at your income before the loan can be approved.
Why This Can Delay Your Closing
When you apply for a mortgage, your lender qualifies you based on your income, employment history, and the likelihood that your income will continue.
If those things change before closing, underwriting may need to verify the new employment and determine whether the income is still eligible under mortgage guidelines.
Depending on the situation, your lender may need:
- An updated offer letter
- Recent pay stubs
- A written verification of employment
- Additional documentation explaining how you’re paid
The more significant the employment change, the more documentation may be required.
Some Changes Are More Complicated Than Others
For example:
- Changing from one hourly job to another in the same field may require very little additional documentation.
- Changing from one hourly job into another where the hours fluctuate may severely impact your income and qualification.
- Changing from an hourly position to a salary position may strengthen your loan if it’s a pay increase.
- Moving from a salaried position to a commission-based job can significantly change how your income is calculated and may kill your loan.
- Becoming self-employed before closing can create entirely new underwriting requirements and kill your loan.
- Changing industries or accepting a position with bonuses, commissions, or overtime may require your lender to evaluate your income differently.
The Best Thing You Can Do
If you’re thinking about changing jobs while your mortgage is in process, talk to your loan officer first.
Many employment changes have little impact on a loan. Others are much easier to navigate when everyone knows about them ahead of time. A five-minute conversation before accepting a new position can save days—or even weeks—of unnecessary delays.
Quick Tip: Never assume a job change is either “fine” or “a deal breaker.” Every situation is different. Your loan officer can often tell you what documentation will be needed before you make the move.
- Commission, bonus, self-employment, or changing industries can require additional documentation.
7. Opening New Credit Before Closing
Buying a new home is exciting, and it’s tempting to start shopping for everything you’ll need. New furniture, appliances, televisions, and even a new vehicle can all seem like reasonable purchases while you’re waiting to close.
Unfortunately, this is one of the quickest ways to delay—or even jeopardize—your mortgage approval.
Your mortgage was approved based on your financial situation at the time you applied. When you open new credit before closing, you’re changing the very information your lender used to qualify you.
It’s More Than Just the Monthly Payment
Many borrowers assume a new purchase won’t matter because the payment is small.
For example:
- Furniture with “No Payments for 12 Months”
- A new appliance financed at 0% interest
- A Buy Now, Pay Later purchase
- A new credit card with a promotional offer
The problem isn’t just the payment. Opening new credit can:
- Lower your credit score.
- Increase your monthly debt obligations.
- Change your debt-to-income ratio.
- Create additional underwriting conditions.
- Require your lender to update your loan approval.
Sometimes that change is minor. Other times, it can affect whether you still qualify for the loan.
Soft Inquiries vs. Hard Inquiries
Not every credit inquiry affects your mortgage.
A soft inquiry—such as checking your own credit score or receiving a pre-qualified offer—doesn’t impact your credit score and generally isn’t a concern.
A hard inquiry occurs when you actually apply for new credit, such as:
- Credit cards
- Furniture financing
- Auto loans
- Personal loans
- Retail store financing
Hard inquiries can affect your credit score, and if new credit is opened, it becomes part of your financial profile.
Your Lender May Check Again Before Closing
Many borrowers assume that once the lender pulls their credit at the beginning of the loan process, that’s the last time anyone looks at it.
That’s not the case.
Most lenders use fraud detection and credit monitoring tools—often referred to as Fraud Guard—throughout the mortgage process. These systems are designed to alert the lender if something significant changes after your initial application, such as a new credit inquiry, a newly opened account, or additional debt.
This isn’t because the lender thinks you’ve done something wrong. It’s because they’re required to make sure your financial picture hasn’t materially changed before they fund your loan.
If the system detects new activity, underwriting may need to stop and review your file again before you can close.
Every “Great Deal” Is a Potential Mortgage Delay
Holiday sales, furniture promotions, appliance packages, and “Buy Now, Pay Later” offers can be incredibly tempting.
Memorial Day.
Fourth of July.
Labor Day.
Black Friday.
They all promise the same thing:
“This deal is too good to pass up!”
But until you’ve closed on your home, every financing promotion is an opportunity to derail your mortgage.
That zero-percent financing offer or “no payments for 24 months” promotion may be an incredible deal—but it won’t feel like much of a bargain if it delays or jeopardizes your home purchase.
I’ve seen borrowers finance furniture because they wanted everything delivered before move-in day, only to create last-minute underwriting conditions that could have been avoided by waiting a few more days.
My advice is simple: if it requires a credit application, don’t do it until after you’ve signed your closing documents and the home is officially yours.
Quick Tip: The best time to finance new furniture, appliances, or electronics is the day after your mortgage closes—not the day before. Your dream home will still be there, and that great deal won’t matter if it costs you the house.
8. Going on Vacation While Your Mortgage Is in Process
This one absolutely blows my mind because it happens every year.
A buyer gets their offer accepted.
Everything is moving along nicely.
Then they leave for a week-long cruise, fly to Mexico, or head to the beach…
…and forget they still have a mortgage loan that’s actively working its way through underwriting.
Your Mortgage Doesn’t Go on Vacation
The mortgage process doesn’t stop just because you’re out of town.
While you’re relaxing on the beach, your loan officer may be trying to reach you because underwriting needs:
- An updated bank statement
- A Letter of Explanation
- An additional pay stub
- A missing signature
- An insurance binder
- Clarification on a recent deposit
Those requests often have to be satisfied before the file can move forward.
If you don’t have internet access, can’t retrieve documents, or simply don’t check your email for several days, your loan may sit untouched until you return home.
Vacation Spending Can Create New Problems
There’s another issue many borrowers don’t consider.
Vacations can be expensive.
It’s not uncommon for buyers to spend thousands of dollars on airfare, hotels, restaurants, and entertainment just days before closing.
If those vacation expenses come from the same funds you’re using for your down payment and closing costs, you may no longer have enough money available to complete your purchase.
Buyers may put funds aside for closing which means they moved money like we talked about earlier. And if the loan approval required a certain amount of reserves, if an updated statement is needed, this can become a big issue.
I’ve also seen buyers put vacation expenses on newly opened credit cards or promotional financing, creating the exact kind of new debt that we talked about in the previous section.
Sellers Aren’t Immune Either
This advice isn’t just for buyers.
I’ve seen sellers leave the country the week before closing, only to discover they needed to sign an updated document, answer a title question, or approve a last-minute change.
Closing day doesn’t care whether you’re sitting in your office or on a beach in Cancun.
How to Avoid It
If you’re planning to travel while buying or selling a home, let your loan officer know as early as possible.
We’ll do everything we can to anticipate document requests before you leave and discuss the best way to reach you if something unexpected comes up.
If possible, avoid scheduling vacations during the final few weeks before closing. If travel can’t be avoided, make sure you’ll have reliable internet access, access to your financial documents, and the ability to electronically sign paperwork if needed.
9. Ignoring or Misunderstanding Underwriting Requests.
One of the biggest misconceptions borrowers have is:
“Didn’t I already send that?”
Sometimes you did.
But underwriting may need:
- An updated bank statement because the previous one is now too old.
- A clearer copy because the original couldn’t be read.
- All pages of a statement instead of just the first page.
- A Letter of Explanation that answers a specific underwriting question.
It isn’t because anyone thinks you did something wrong.
It’s because mortgage guidelines require the underwriter to document specific items before they can approve your loan.
The “Apple and Banana” Problem
Loan officers joke about this all the time.
We ask for an apple.
The borrower sends us a banana.
Well…at least they’re both fruit.
So we ask again.
This time we get an orange.
We explain one more time exactly what underwriting needs…
…and somehow we receive a sandwich.
Meanwhile, underwriting is still waiting for the apple.
It sounds funny, but this happens every day.
The underwriter isn’t looking for any document. They’re looking for a specific document that satisfies a specific guideline.
More Isn’t Always Better
The opposite problem happens just as often.
We ask for one pay stub.
The borrower uploads:
- Twenty pay stubs
- Three years of tax returns
- Six months of bank statements
- Retirement account statements
- Their electric bill
- And a copy of their dog’s vaccination records.
Okay…maybe not the last one.
But you get the idea.
Providing far more documentation than requested doesn’t speed things up. In fact, it often slows things down because someone has to sort through everything to find the one document underwriting actually requested.
How to Avoid It
When your loan officer requests documentation, read the request carefully.
If we ask for the most recent pay stub, send the most recent pay stub.
If we ask for pages 1 through 8 of your bank statement, send all eight pages.
If you’re not sure exactly what’s being requested, don’t guess.
Ask.
A 30-second phone call is much faster than three rounds of sending the wrong documents.
Quick Tip: Your loan officer isn’t looking for “more paperwork.” They’re looking for the right paperwork. Sending exactly what’s requested is one of the fastest ways to keep your mortgage moving toward the closing table.
10. Waiting Until the Last Minute for Everything
There’s a common theme running through almost every item on this list.
Very few mortgage delays happen because one big thing went wrong.
Most delays happen because a series of small tasks were all pushed until the last minute.
Buying a home isn’t just about qualifying for a loan. It’s a coordinated effort involving your loan officer, processor, underwriter, realtor, title company, insurance agent, appraiser, employer, and sometimes even your bank. Every person has a role, and every role has its own timeline.
When one person waits until the last minute, everyone else loses the time they needed to do their job.
Last-Minute Tasks That Commonly Cause Problems
Some of the most common examples include:
- Waiting until the day of closing to wire your cash to close.
- Waiting until the last minute to provide updated bank statements or pay stubs requested by underwriting.
- Delaying homeowners insurance until just before closing.
- Waiting until the last minute to verify employment changes or explain large deposits.
- Waiting to obtain a cashier’s check after your lender has provided closing instructions.
- Assuming everything is “good to go” instead of checking in with your loan officer before closing week.
None of these tasks are difficult.
The problem is that if something unexpected happens—a bank wire cutoff time is missed, your insurance agent is unavailable, or the title company needs updated figures—there’s no extra time left to solve the problem.
Give Yourself a Buffer
One of the best ways to reduce stress during the mortgage process is to stop treating every deadline as the actual deadline.
If you need to wire your funds by Friday, plan to send them on Wednesday.
If you need homeowners insurance before closing, have it completed during the first week after your contract is accepted.
If documents are requested today, return them today—not tomorrow.
Building even a small buffer into your schedule gives everyone involved time to solve unexpected issues without putting your closing date at risk.
Quick Tip: A smooth closing rarely happens because everything goes perfectly. It happens because everyone leaves enough time to handle the unexpected.
Think of your closing date like a flight departure.
If your plane leaves at 8:00 a.m., you don’t plan to arrive at the airport at 7:59.
You build in extra time for traffic, security, and anything unexpected.
Your mortgage works the same way.
Closing day isn’t the day to start gathering documents, shopping for insurance, wiring funds, or asking questions. It’s the day everything should already be finished.
The borrowers who have the smoothest closings aren’t the luckiest. They’re the ones who stay a few steps ahead throughout the process
Some Delays Aren't Your Fault
While this article has focused on delays borrowers can prevent, it’s important to remember that not every delay is within your control.
Sometimes a closing is delayed because of circumstances elsewhere in the transaction, such as:
- Appraisal scheduling or appraisal revisions.
- Title work uncovering liens, ownership issues, or legal questions.
- The seller not completing agreed-upon repairs or paperwork.
- Severe weather delaying inspections, appraisals, or closings.
- HOA questionnaires, resale certificates, or other required association documents taking longer than expected.
The good news is that these situations are usually temporary, and your loan officer, real estate agent, title company, and lender will work together to resolve them as quickly as possible.
This article focused on the delays you can prevent—because those are often the easiest to avoid with good communication and a little preparation.
In my next article, I’ll cover 10 mortgage closing delays that borrowers can’t control—and what happens when they occur.
How to Keep Your Mortgage Closing on Schedule
Buying a home doesn’t have to be stressful. Most mortgage delays can be avoided by staying engaged throughout the process and responding quickly when your lender needs something.
If you remember nothing else from this article, remember these six rules:
✅ Treat every request from your loan officer as time-sensitive.
✅ Read emails, answer calls, and sign disclosures as soon as you receive them.
✅ Don’t make major financial changes without talking to your loan officer first.
✅ Keep your money and your employment as stable as possible until after closing.
✅ Start shopping for homeowners insurance early.
✅ When you’re unsure about something, ask before you act—not after.
Most importantly, remember that your loan officer isn’t asking for documents to make your life difficult. Every request is intended to satisfy a specific underwriting requirement and keep your loan moving toward the closing table.
Need Help Keeping Your Mortgage on Track?
Every mortgage is different, but one thing never changes: good communication makes the process smoother.
If you’re buying a home in KY, IN, FL or MN and have questions about your mortgage, I’m happy to explain what to expect, answer your questions, and help you avoid the common mistakes that delay closings.
Whether you’re buying your first home or your fifth, my goal is simple: help you get to the closing table as smoothly as possible.
Have questions? Contact Musketeer Mortgage today, and let’s keep your mortgage moving forward
Call us Directly
Text us for a Quick Response