

VA IRRRL Streamline Refinance
By Shawn Neely, Owner & CEO, Musketeer Mortgage LLC — NMLS #1416990
Last updated: August 29, 2026
If you’re getting letters, calls, or refinance offers about your VA loan, the hard part usually isn’t finding someone willing to refinance it. The hard part is knowing whether the offer actually makes sense.
A VA IRRRL can be an excellent refinance, but a lower rate by itself does not make an offer a good deal. VA has specific rules covering how long you must have the current loan, how many payments you must make, how much the rate must improve, and how quickly certain refinancing costs must be recovered.
I’m a retired Army Major and a mortgage broker, and I built this page the way I would want another veteran to receive the information: show me the rules, show me the math, and show me the tradeoffs. My goal is to give you enough information to evaluate any IRRRL offer for yourself—including one from me—before you decide whether refinancing is actually worth doing.
VA IRRRL Key Takeaways
- Your current mortgage must already be a VA-backed loan. An IRRRL cannot refinance a conventional, FHA, or USDA mortgage, and it is a rate-and-term refinance—not a cash-out loan.
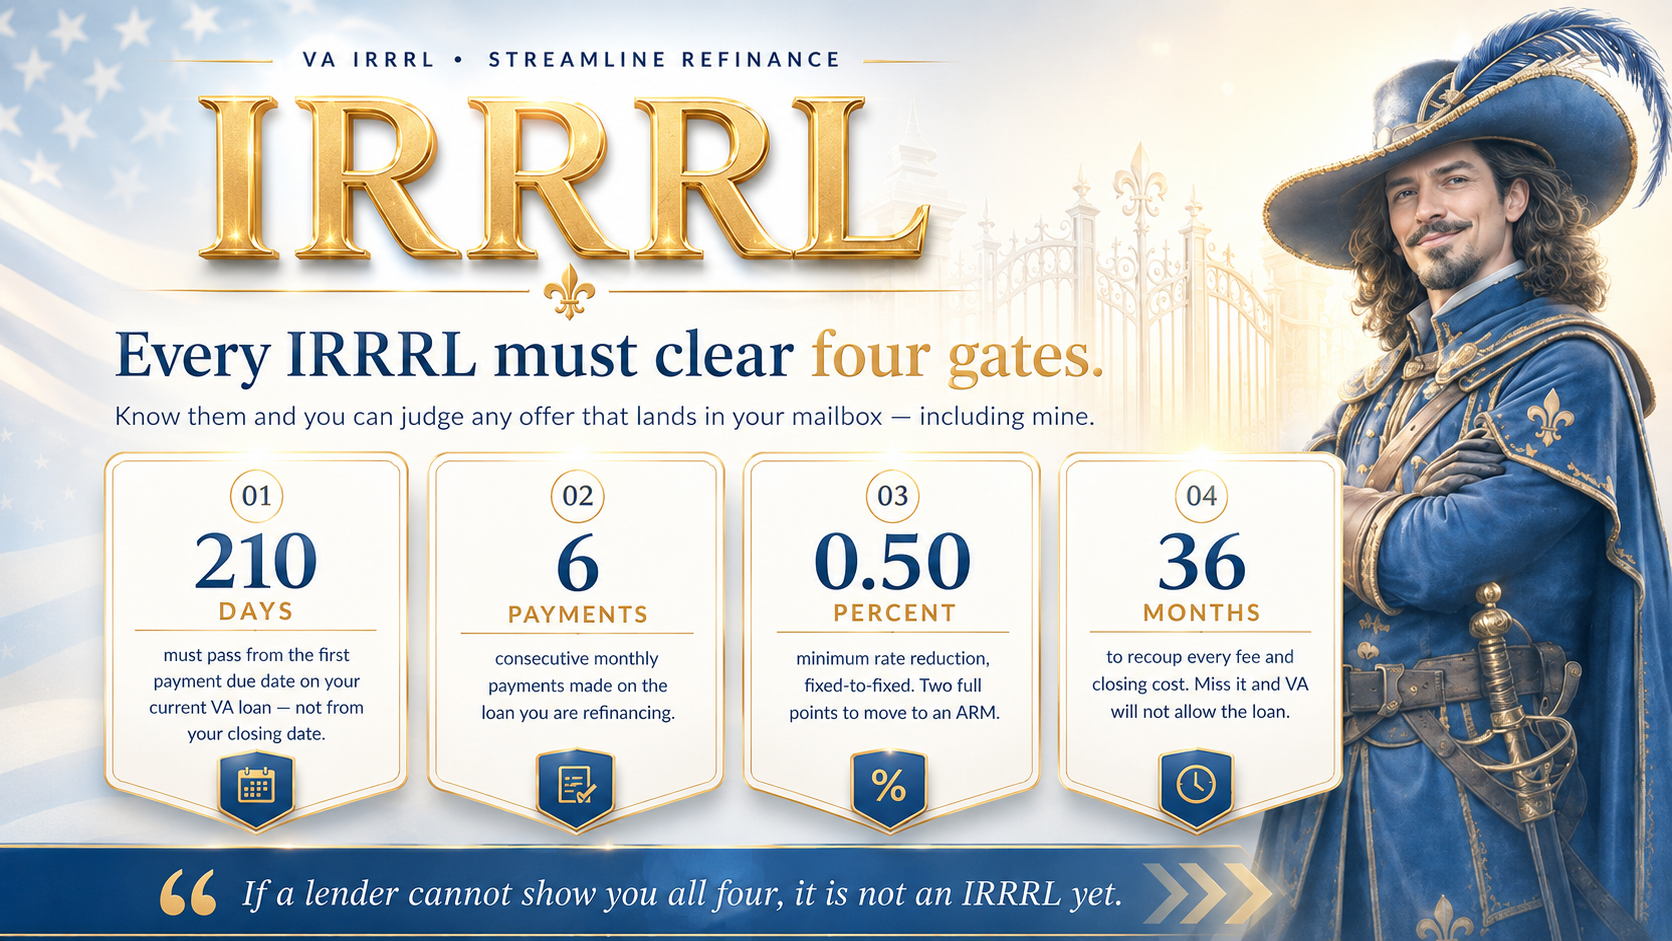
- You must satisfy both seasoning requirements: at least 210 days from the first payment due date on your current VA loan and 6 consecutive monthly payments made before the new loan closes.
- The rate improvement has a minimum. A fixed-rate VA loan generally must drop by at least 0.50%, while moving from a fixed rate to an ARM requires at least a 2.00% reduction.
- If your principal-and-interest payment goes down, eligible refinancing costs must be recovered within 36 months. If the payment stays the same or increases, VA applies a different—and stricter—cost rule.
- The VA IRRRL funding fee is 0.50% of the loan amount. Many veterans with qualifying service-connected disability benefits are exempt, and some veterans who paid the fee may later qualify for a refund.
- You do not necessarily have to live in the home today. Prior occupancy can satisfy the IRRRL occupancy requirement, which can make the program useful for veterans who PCS’d and kept the home as a rental.
- VA itself sets no minimum credit score for an IRRRL. Individual lenders can impose their own requirements, with lender credit-score overlays commonly falling in the 580–640 range.
What a VA IRRRL Is — and What It Is Not
A VA Interest Rate Reduction Refinance Loan—usually called an IRRRL or VA Streamline Refinance—is a refinance specifically for homeowners who already have a VA-backed mortgage. It is designed to replace that existing VA loan with another VA loan under new terms. You cannot use an IRRRL to refinance an FHA, conventional, or USDA mortgage, and you cannot use it to pull equity out of the home as cash. If your mortgage isn’t a VA loan, your other refinance options are the place to start.
That distinction matters because “streamline” describes the refinancing process, not a shortcut around VA’s rules. An IRRRL still has to meet specific requirements intended to make sure the new loan provides a legitimate benefit to the veteran. Some of the documentation normally associated with a mortgage may not be required by VA, but that does not mean every lender will handle an IRRRL the same way.
If you are still learning how the VA mortgage program works more broadly, my VA loans for veterans guide explains the underlying VA loan benefit in more detail. This page stays focused on one question: when does refinancing an existing VA loan through an IRRRL actually make sense?
What an IRRRL Does Not Require
One of the reasons the IRRRL is called a “streamline” refinance is that VA itself does not require many of the items normally associated with a purchase loan or a traditional refinance.
For an IRRRL, VA typically does not require a new appraisal or income documentation. The program is built around refinancing an existing VA-backed loan rather than qualifying the borrower and property from scratch.
That does not mean every IRRRL is completely documentation-free. Loans still have to meet the requirements of the lender, investor, and the specific loan program being used. In practice, many of those requirements are fairly consistent across the mortgage industry, even when they are not specifically written into the VA guideline itself.
The better way to think about an IRRRL is this: VA removes much of the traditional underwriting burden, but the loan still has to meet normal lending standards before it can close.
VA Requirements vs. Industry Lending Standards
There is an important distinction between what VA specifically requires and what lenders commonly require to make an IRRRL eligible for purchase or delivery.
For example, VA does not establish a minimum credit score for an IRRRL. In practice, however, lenders generally do have minimum credit standards to mitigate investment risk, and minimum credit-score requirements commonly fall in the 580–640 range. Those requirements are widespread enough that a veteran should not assume a lender is creating an unusual obstacle simply because the requirement does not appear in VA’s published rule.
You Do Not Have to Live There Anymore
The occupancy rule for an IRRRL is also different from what many veterans expect.
For an IRRRL, you must certify that you currently live in the property or previously lived in it. Current occupancy is not required.
That can be particularly important for veterans who used a VA loan to buy a home at one duty station, later received PCS orders, moved away, and kept the former home as a rental. Moving out does not automatically eliminate the ability to refinance that existing VA loan through an IRRRL.
For veterans dealing with a move to or from the Fort Knox area, my Fort Knox VA loan guide covers the broader VA financing considerations that come with military relocation.
The First Three Gates Every IRRRL Must Clear
Before an IRRRL can move forward, there are three basic eligibility tests that have to be satisfied. These are not judgment calls, and they are not things a lender can simply waive because the refinance otherwise looks good.
Two of them deal with how long you have had the current VA loan and how many payments you have made. The third deals with whether the new interest rate improves enough to meet VA’s net tangible benefit requirement.
210 Days From Your First Payment Due Date
The 210-day clock starts with the first payment due date on your current VA loan—not the date you closed on it. The new IRRRL cannot close until at least 210 days have passed from that first payment due date.
That distinction can move the eligible refinance date by a month or more.
For example, suppose you closed on your VA purchase loan in April, but your first payment was due June 1. The seasoning clock begins June 1. It does not begin on the April closing date. That means the earliest possible IRRRL closing would fall roughly in December, once the full 210-day requirement has been satisfied.
This is why looking only at the date you bought the house can give you the wrong answer.
Six Consecutive Monthly Payments
The 210-day requirement is only half of the seasoning test. You must also have made six consecutive monthly payments on the VA loan being refinanced before the IRRRL closes.
Both conditions have to be met.
That means you do not become eligible simply because six payments have been made, and you do not become eligible simply because 210 days have passed. VA requires the loan to satisfy both the time requirement and the payment requirement as of the new closing date.
The Required Rate Reduction
An IRRRL also has to provide enough of an interest-rate improvement to meet VA’s minimum requirement.
For a fixed-rate VA loan being refinanced into another fixed-rate loan, the new interest rate must be at least 0.50 percentage points lower, than the rate on the loan being refinanced.
For a fixed-rate loan being refinanced into an adjustable-rate mortgage, the reduction must be at least 2.00 percentage points.
So a rate that is technically lower is not automatically enough. VA sets a minimum improvement before the refinance can qualify as an IRRRL.
Once those first three gates are cleared, there is still one more question to answer: do the costs of the refinance meet VA’s consumer-protection rules? That is where the 36-month recoupment test comes in.
The Fourth Gate: VA's Cost-Protection Rules
Clearing the seasoning and rate-reduction requirements does not automatically make an IRRRL a good refinance. VA also places limits on the costs a veteran can incur in relation to the benefit the new loan provides.
This fourth gate works a little differently from the first three because the rule depends on what happens to your new monthly principal-and-interest payment. If the payment decreases, VA applies a 36-month recoupment test. If the payment stays the same or increases, a different and more restrictive cost rule applies.
The purpose is straightforward: an IRRRL should provide a real financial benefit to the veteran, not simply create another mortgage transaction.
When Your Payment Drops: The 36-Month Recoupment Rule
If the new IRRRL lowers your monthly principal-and-interest payment, the fees, closing costs, and expenses subject to VA’s recoupment calculation must be recovered through that monthly savings within 36 months of closing.
Think of recoupment as the amount of time it takes for the monthly savings created by the refinance to earn back the costs you paid to get those savings.
That matters because a lower payment can look attractive by itself. But if you spend thousands of dollars to reduce the payment only slightly, it could take years before you actually get back to even. VA does not allow an IRRRL that takes longer than 36 months to recover the costs included in its recoupment test.
This is one of the most useful numbers on an IRRRL. When someone shows you how much the payment may decrease, the next question should be:
“How many months will it take me to recover the costs of getting that savings?”
What Counts Toward Recoupment — and What Does Not
Not every dollar associated with the new closing is included in VA’s 36-month calculation.
VA excludes the VA funding fee, escrow deposits, and prepaid expenses from the recoupment test. Prepaid expenses can include items such as insurance, taxes, special assessments, and homeowners association fees.
That distinction is important. Your total amount due at closing or the total increase in your loan balance is not necessarily the number you divide by your monthly savings.
The recoupment calculation is designed to measure the cost of obtaining the refinance itself against the financial benefit created by the lower principal-and-interest payment.
So when reviewing an IRRRL offer, make sure you are comparing the right numbers. A lender’s recoupment worksheet should separate the costs included in VA’s calculation from the amounts VA specifically excludes.
When Your Payment Stays the Same or Goes Up
Not every beneficial refinance lowers the monthly payment. A veteran may choose to shorten the loan term, for example, which can cause the new principal-and-interest payment to stay the same or increase even though the interest rate is lower.
When that happens, VA does not use the normal 36-month recoupment test. Instead, the veteran cannot incur the ordinary fees, closing costs, and expenses associated with the refinance, other than the items VA specifically allows.
That does not mean the transaction itself has no closing costs. Title work, lender charges, recording charges, and other legitimate costs may still exist. A lender credit can potentially offset those costs so that the veteran does not incur them.
But this is also where an IRRRL may stop being the best tool.
If your goal is to reduce both your interest rate and the length of your mortgage, the lender may have to price the IRRRL high enough to generate the credit necessary to absorb those closing costs. That can work against the very rate improvement you were trying to achieve.
In that situation, it may make sense to compare the IRRRL with a fully underwritten refinance instead. Within the VA program, that alternative is generally treated as a VA cash-out refinance—even if you are not actually taking cash from the property. VA’s Type I cash-out refinance can be structured without equity withdrawal, and allowable fees and charges may be paid from the loan proceeds. Unlike an IRRRL, however, it requires an appraisal and full credit underwriting.
That can create a legitimate tradeoff:
IRRRL: streamlined underwriting, but the same-or-higher-payment cost restriction may make shortening the term difficult to price attractively.
Fully underwritten refinance: more documentation and underwriting, but potentially greater flexibility to finance allowable closing costs while pursuing both a lower rate and shorter term.
That does not mean the fully underwritten refinance is automatically better. It means that once the veteran’s objective changes from simply lowering the payment to paying the mortgage off substantially faster, the right question becomes bigger than, “Can I do an IRRRL?”
The better question is: Which refinance structure produces the best overall financial result?
Running the Numbers on Your Own IRRRL
The basic recoupment calculation is simple:
Costs subject to recoupment ÷ monthly principal-and-interest savings = months to recoup
Here is a purely illustrative example.
Suppose the costs included in VA’s recoupment calculation are $3,000, and the new loan reduces principal and interest by $150 per month.
$3,000 ÷ $150 = 20 months
In that example, it takes 20 months for the monthly savings to recover the costs of the refinance. Because 20 months is less than VA’s 36-month maximum, it clears that portion of the IRRRL requirement.
Now suppose the same $3,000 in costs produced only $75 per month in savings:
$3,000 ÷ $75 = 40 months
That does not clear the 36-month requirement.
The math is simple. Getting the correct numbers to put into the equation is where the details matter. Your actual payoff, qualifying closing costs, current principal-and-interest payment, and proposed new loan all affect the result.
That is also why I do not think you should accept a statement such as “this loan will save you money” without seeing the calculation behind it.
If you want me to run the actual numbers on your VA loan, I’ll show you the costs, the monthly difference, and the recoupment period so you can see for yourself whether the refinance makes sense.
What “No-Cost” VA Refinancing Actually Means
“No-cost refinance” is one of those mortgage phrases that sounds simpler than it really is.
An IRRRL can often be structured so that you bring little or no money to closing. VA specifically allows eligible IRRRL costs to be included in the new loan, or the lender can structure the interest rate high enough to generate a lender credit that pays the closing costs.
Those are very different ways of getting to the same result: little or no cash out of your pocket at closing.
But neither automatically means the refinance has no cost.
Rolling the Closing Costs Into the New Loan
One option is to add allowable closing costs to the new IRRRL balance rather than paying them at closing. VA permits allowable closing costs, including the VA funding fee, to be included in an IRRRL subject to the program’s limitations.
That solves the cash-at-closing problem, but you are still paying the costs. They have simply become part of the mortgage.
If you owe $X today and the new loan balance is higher because closing costs were added, that difference matters. You will be paying interest on the financed amount as you repay the new loan.
That doesn’t make financing the costs a bad decision. Sometimes preserving your cash is exactly what makes sense. It just shouldn’t be confused with the costs disappearing.
If you would rather pay them at closing than finance them, here’s what that changes.
Using a Lender Credit to Pay the Closing Costs
The other common approach is a lender credit.
Instead of adding the closing costs to your loan balance or asking you to pay them out of pocket, the lender provides a credit that offsets some or all of those costs.
This is the concept we discussed in the previous section:
Closing costs exist → lender credit pays them → you do not pay those costs directly.
VA specifically permits a lender to set the new loan’s interest rate high enough to enable the lender to pay the closing costs, as long as the IRRRL still satisfies VA’s other requirements.
That lender credit is not free money. Mortgage pricing involves tradeoffs. Generally, obtaining more lender credit means accepting less favorable pricing (a higher interest rate) than you could have received if you were willing to pay more of the costs yourself.
And that is why I don’t like evaluating an IRRRL based solely on whether someone calls it “no cost.”
The better question is: Where did the cost go?
Three Questions to Ask About Any “No-Cost” IRRRL
If someone offers you a no-cost VA refinance, ask them to show you these three things:
- Are any closing costs being added to my new loan balance?
If they are, find out exactly how much the balance is increasing and what those costs consist of. - Is a lender credit paying any of my closing costs?
If so, ask how much the credit is and how the loan’s pricing would change if you chose a smaller lender credit and paid more of the costs yourself. - What is my actual recoupment period?
If your principal-and-interest payment is decreasing, the lender should be able to show you how the applicable refinancing costs compare with your monthly savings and whether the loan satisfies VA’s 36-month requirement.
There isn’t one universally correct way to structure these costs. A veteran who wants to preserve cash may prefer financing allowable costs. And this is how the vast majority of IRRRLs are structured. Another may prefer paying more upfront to obtain better loan pricing. A third may choose lender-paid costs because that structure works best for how long they expect to keep the mortgage (the math usually doesn’t support this option, so keep that in mind. It’s technically possible, but mathematically unlikely in most cases.).
The important part is that you understand the trade.
“No money out of pocket” describes what happens at closing. It does not necessarily describe what the refinance ultimately costs you.
And if the new principal-and-interest payment stays the same or increases, remember that the special cost-protection rule discussed above applies instead of the normal 36-month recoupment test.
The VA IRRRL Funding Fee
VA charges a 0.50% funding fee on an IRRRL.
That fee is based on the new loan amount and can generally be financed into the new mortgage rather than paid out of pocket at closing. Compared with other types of VA financing, the IRRRL funding fee is relatively small, but it is still a real cost and should be included when you evaluate the overall refinance.
More importantly, not every veteran has to pay it.
Who Does Not Pay the IRRRL Funding Fee
You may be exempt from the VA funding fee if you fall into one of VA’s qualifying exemption categories.
That includes veterans who are:
- Receiving VA compensation for a service-connected disability.
- Eligible to receive VA disability compensation but are receiving retirement or active-duty pay instead.
- Surviving spouses receiving Dependency and Indemnity Compensation, commonly called DIC.
- Service members who have received a proposed or memorandum disability rating from VA before the loan closes.
- Active-duty service members who provide evidence of receiving a Purple Heart on or before closing.
If you are exempt, the 0.50% IRRRL funding fee should not be charged.
This is something I want verified early in the refinance process. A funding-fee exemption can affect the new loan amount, and there is no reason to finance a fee that VA says you do not owe.
The Retroactive Disability Rating Refund
There is another funding-fee rule that many veterans never hear about.
Suppose you close your IRRRL and pay the VA funding fee because you are not considered exempt at the time of closing. Later, VA grants you compensation for a service-connected disability.
You may be entitled to a refund of the funding fee if the effective date of that disability compensation is retroactive to a date before your IRRRL closing.
The important date is not simply when VA approves the disability claim. The important date is the effective date of the award.
For example, imagine an IRRRL closes while a disability claim is still pending. Months later, VA approves the claim, but assigns an effective date that falls before the refinance closing date. In that situation, the veteran may qualify to have the funding fee refunded.
There is an important limitation here: a proposed or memorandum rating issued only after the loan has already closed does not, by itself, create refund eligibility. The later award needs an effective date that reaches back to before the closing.
If you paid a VA funding fee and later received a service-connected disability award, it is worth checking the effective date on your VA decision. That date may determine whether money you already paid can be returned to you.
Choosing the Right Strategy for Your VA IRRRL
The IRRRL’s natural strength is lowering the rate and payment. And a lower rate can do more than reduce your monthly payment. It can also give you flexibility in how quickly you pay the mortgage off.
For many veterans, the straightforward IRRRL strategy is to refinance into a new 30-year loan, reduce the interest rate and required monthly payment, and then decide what to do with the savings.
You are not required to spend that savings.
If your current principal-and-interest payment is comfortable, you can continue paying roughly what you were paying before and direct the difference toward principal. That gives you the security of a lower required payment while still allowing you to pay the mortgage down faster.
For example, if an IRRRL reduces your required payment, you have two choices:
- Keep the savings each month and improve your household cash flow.
- Apply some or all of the savings back to principal and accelerate the payoff of the new loan.
You can also change that strategy over time. During a month when cash is tight, you have the benefit of the lower required payment. When your budget allows, you can make additional principal payments.
What If You Don’t Want to Start Over at 30 Years?
This is a legitimate concern, especially if you have already been paying on your current mortgage for several years.
If you are far enough into your existing loan that restarting a new 30-year amortization does not fit your goals, the IRRRL may not be the only refinance option worth considering.
A fully underwritten refinance can allow us to compare a loan term closer to the number of years you currently have remaining while still pursuing a lower interest rate. That route involves more traditional underwriting than an IRRRL, but it may make more sense when maintaining your existing payoff schedule is the priority.
The other option is often much simpler: use the IRRRL to lower the required rate and payment, then voluntarily continue making a larger payment by applying the savings toward principal.
That can give you the best of both worlds:
A lower required payment when you need the flexibility, with the ability to pay the loan down faster when you don’t.
The point is not to automatically choose a new 30-year loan or automatically avoid one. It is to look at where you are in your current mortgage, what the IRRRL saves you, and what you want the new loan to accomplish.
Discount Points on a VA IRRRL
Discount points can be used on a VA IRRRL, but VA limits how much can be included in the new loan.
The rules depend partly on the loan-to-value ratio:
- Up to 1 discount point may be included when the new loan is at or below 100% loan-to-value.
- More than 1 point may be included only when the loan-to-value is at or below 90%.
- No more than 2 discount points may be included in the IRRRL loan amount.
VA also allows points when the lower interest rate results partly from an improvement in market conditions.
The practical takeaway is that paying points to obtain a lower rate is allowed, but there are limits on how much of that cost can be rolled into the new VA loan. The more points involved, the more important it becomes to look at the entire refinance—not just the interest rate.
A lower rate may look attractive, but if you are paying substantial points to get it, those costs still need to make financial sense and, when the new principal-and-interest payment is lower, they must still fit within VA’s 36-month recoupment requirement.
IRRRL vs. VA Cash-Out Refinance
An IRRRL and a VA cash-out refinance are both VA refinance options, but they are built for very different jobs.
An IRRRL is primarily about improving the terms of a VA loan you already have—usually by lowering the interest rate and principal-and-interest payment. It is intentionally streamlined, which is why VA generally does not require the appraisal, income qualification, or full credit underwriting associated with a traditional refinance.
A VA cash-out refinance is a fully underwritten VA refinance. Despite the name, you do not necessarily have to take cash out. It can also be used when you want the flexibility of a traditional refinance structure, such as refinancing a non-VA mortgage into VA financing or pursuing a refinance that does not fit within the IRRRL rules.
If you actually want to pull equity from the home, however, an IRRRL is not an option. An IRRRL does not allow cash out.
The important question is not which program sounds better. It is what are you trying to accomplish?
- If you already have a VA loan and simply want to lower the rate and payment, the IRRRL is usually the first option to evaluate.
- If you need cash from your equity, the VA cash-out refinance is the appropriate VA program.
- If the structure you want does not work under IRRRL rules, a fully underwritten refinance may give you more flexibility.
How an IRRRL Compares With Other Refinance Programs
| Comparison | VA IRRRL | VA Cash-Out Refinance | Conventional Rate/Term | FHA Streamline |
|---|---|---|---|---|
| Existing loan required | Must already be a VA-backed loan | Can refinance VA or other eligible existing mortgages | Can refinance different types of existing mortgages if conventional guidelines are met | Must already be FHA-insured |
| Appraisal | VA generally does not require one | Required | Usually required, although an eligible appraisal waiver may be available | FHA generally does not require one for a streamline |
| Income documentation | VA generally does not require traditional income qualification | Full income qualification | Full income qualification | Non-credit-qualifying versions generally do not require traditional income qualification |
| Credit qualifying | No VA credit-underwriting package required, although lender requirements still apply | Yes | Yes | Available as credit-qualifying or non-credit-qualifying |
| Cash out allowed | No | Yes | Not with a standard rate/term refinance beyond permitted incidental cash back | No meaningful cash out; FHA limits incidental cash back |
| Can work when home value has fallen | Potentially, because VA generally does not require an appraisal | Limited by the home’s VA reasonable value | Generally subject to conventional LTV limits | Potentially, particularly with a non-appraisal streamline |
| Program fee | 0.50% VA funding fee, unless exempt | VA funding fee applies unless exempt and is higher than the IRRRL fee | No VA or FHA funding fee; other conventional pricing and mortgage-insurance rules may apply | FHA mortgage-insurance requirements apply |
| Underwriting level | Streamlined | Full VA underwriting | Full conventional underwriting | Streamlined, with credit-qualifying and non-credit-qualifying options |
| Process | Usually the most streamlined VA refinance | Similar to a traditional fully underwritten mortgage | Traditional refinance process | Streamlined FHA refinance process |
The table makes one thing clear: the IRRRL gives up some flexibility in exchange for simplicity.
You cannot use it to refinance a conventional or FHA loan. You cannot pull equity out as cash. And the new loan has to satisfy VA’s specific IRRRL benefit and cost-protection requirements.
In return, an eligible veteran can potentially refinance an existing VA loan without going back through the full appraisal and income-qualification process required on a traditional refinance.
That is why I view the IRRRL as a very specific tool rather than simply another refinance program. When your goal matches what it was designed to do—lower the rate and payment on an existing VA loan—it can be exceptionally efficient. When your goal falls outside those boundaries, another refinance structure may make more sense.
How to Spot a Bad VA Refinance Offer
Veterans with VA loans receive a lot of refinance solicitations. Some are legitimate. Some are carefully designed to look more official, more urgent, or more financially attractive than they really are.
VA itself warns veterans about refinance offers that promise things such as skipped mortgage payments, unusually low rates, large escrow refunds, cash back, “no-cost” refinancing, repeated refinances without a waiting period, or guaranteed approval regardless of credit.
The fact that an offer arrives in an official-looking envelope does not make it a VA offer. Your IRRRL will come from a private lender, mortgage company, bank, credit union, or broker—not directly from the Department of Veterans Affairs.
I would pay particularly close attention to these red flags:
- The mailer looks like it came from VA or your current mortgage servicer when it did not. Government-style seals, account information, or language about your “VA benefit” can make advertising look much more official than it actually is.
- “Skip a payment” is presented as savings. Changing when mortgage payments are due is not the same thing as eliminating money you owe. A legitimate refinance should stand on the financial benefit of the new loan—not on the illusion that a payment disappeared.
- Your escrow refund is presented as money created by the refinance. Money remaining in your existing escrow account already belongs to you. Receiving it after the old mortgage is paid off is not the same thing as the lender giving you cash.
- The entire conversation revolves around the new payment. A lower payment is important, but you should also know the closing costs, lender credits, new loan balance, loan term, and recoupment period.
- The lender calls the refinance “no cost” but cannot clearly explain who is paying the costs. As we discussed earlier, costs can be financed or offset with a lender credit. Ask where the costs went.
- The lender cannot clearly show that you satisfy the IRRRL rules. You should be able to see the 210-day seasoning requirement, six-payment requirement, required rate improvement, and applicable cost-protection test in the numbers.
- You are being pressured to decide before you have seen the complete transaction. An IRRRL should make sense after you understand the numbers—not because someone convinced you that an opportunity disappears if you do not act immediately.
- The explanation changes when you start asking questions. A good refinance should become easier to understand as more information is provided, not harder.
The easiest way to protect yourself is to separate the advertisement from the actual loan.
Do not ask only:
“How much will this lower my payment?”
Also ask:
“What will my new loan balance be, what costs am I paying, what lender credits am I receiving, and how long will it take me to recover the costs?”
If those questions cannot be answered clearly, I would not move forward until they can.
Common IRRRL Failure Points
Sometimes the offer itself is legitimate, but the proposed loan still does not meet IRRRL requirements.
These are some of the first things I check when evaluating whether an IRRRL actually works:
The 210-day clock was calculated from the wrong date.
The seasoning period begins with the first payment due date on the existing VA loan, not the date the veteran originally closed.
Six consecutive monthly payments have not been made.
Passing 210 days by itself is not enough. The payment requirement must also be satisfied.
The rate improvement is not large enough.
For a fixed-rate loan refinancing into another fixed-rate loan, the reduction must be at least 0.50 percentage points. A fixed-to-ARM IRRRL requires at least a 2.00 percentage-point reduction.
The costs take too long to recover.
When the new principal-and-interest payment decreases, the costs included in VA’s calculation must generally be recovered within 36 months. A refinance that produces savings but takes too long to earn back its costs does not pass that test.
The payment does not decrease, but the loan is being structured as though the normal recoupment rule still applies.
When principal and interest stay the same or increase, VA’s more restrictive cost rule applies instead. That can completely change whether an IRRRL is the appropriate refinance structure.
The loan meets VA’s basic program rules but not the lender’s lending requirements.
As discussed earlier, VA guidelines and lender requirements are not always identical. Credit standards and other lender or investor requirements can still affect whether a particular lender can close the loan.
This is why I do not start an IRRRL conversation by asking only, “Can I get you a lower rate?”
The better question is:
“Can we structure a refinance that clears every VA requirement and actually improves your financial position?”
If the answer to either part is no, the loan needs to be reworked—or it may not be the right refinance at all.
What You'll Need and How Long an IRRRL Takes
One of the practical advantages of an IRRRL is that the file is usually much lighter than a traditional refinance. VA does not generally require a new appraisal or the full income-and-credit qualification package you would expect on a regular mortgage refinance.
That does not mean there is nothing to collect. Your lender still has to document the existing VA loan, establish the new loan correctly, verify the payoff, prepare disclosures, and complete the normal title and closing process.
Documents You May Need
The exact list can vary by lender and by the circumstances of the loan, but an IRRRL file will commonly start with a relatively short list:
- Your current mortgage statement so the lender can confirm the existing loan information and servicer.
- A government-issued photo ID.
- Your homeowners insurance information so the new lender can verify coverage for the property.
- Your Certificate of Eligibility, if you have it. You generally do not need to obtain a new COE yourself for an IRRRL; the lender can confirm your prior VA entitlement electronically.
- Information about any second mortgage or other lien on the property, if one exists, because it may need to remain subordinate to the new VA loan.
Depending on the lender or something specific about your file, additional documentation may be requested.
For example, a lender may obtain a credit report even though VA does not require a traditional credit-underwriting package for a standard IRRRL. A particular circumstance can also create the need for additional documentation that would not be required on a routine streamline refinance.
The important point is that an IRRRL is streamlined, not undocumented.
The IRRRL Process From Application to Closing
The process itself is fairly straightforward.
1. Review the existing VA loan.
The first step is confirming your current balance, interest rate, payment, first payment due date, and payment history. This tells us whether the loan has satisfied the seasoning requirements.
2. Determine whether refinancing actually improves the loan.
We compare the existing loan with the proposed IRRRL and make sure the required rate reduction and VA cost-protection rules are satisfied.
3. Structure the new loan.
This is where we determine the new loan amount, term, closing costs, lender credits, and whether any allowable costs will be financed.
4. Complete the application and disclosures.
Once you decide to move forward, the lender prepares the formal loan application and required mortgage disclosures.
5. Verify the existing loan and property information.
The lender obtains the mortgage payoff and handles items such as title work, insurance verification, VA eligibility confirmation, and any other documentation needed for the particular transaction.
6. Complete the VA IRRRL calculations.
Before closing, the lender documents the comparison between the old loan and the new loan, including the required benefit and applicable recoupment calculation.
7. Review the final numbers and close.
You receive the final closing documents showing the new loan terms, costs, credits, and amount needed at closing, if any. Once everything is correct, you sign the new mortgage and the old VA loan is paid off.
There is not one VA-mandated number of days that every IRRRL must take from application to closing. Timing depends on the lender, title work, payoff information, required disclosures, and whether anything unusual has to be resolved. Regular refinances generally run two to three weeks; an IRRRL is usually faster because there’s no appraisal to schedule. But title and payoffs are still an x-factor.
Because a standard IRRRL normally avoids a new appraisal and much of the traditional income underwriting, the process can be considerably simpler than a fully underwritten refinance. But I would rather give you a realistic closing expectation based on your actual loan than advertise an arbitrary number of days that may not apply to your situation.
The goal should not be to close an IRRRL as fast as humanly possible. The goal is to close it efficiently while making sure the numbers are right and the refinance actually benefits you.
How to Evaluate Any VA Refinance Offer
By this point, you should have enough information to evaluate an IRRRL without relying on a sales pitch.
When someone presents you with a VA refinance offer, work through these questions in order:
1. Is my current loan already VA-backed?
An IRRRL can only refinance an existing VA loan. If your current mortgage is conventional, FHA, USDA, or another loan type, you need a different refinance program.
2. Have I met both seasoning requirements?
Confirm that:
- At least 210 days have passed since the first payment due date on your current VA loan.
- You have made at least 6 consecutive monthly payments on that loan.
Do not let someone calculate the 210 days from your original closing date.
3. Does the new rate improve enough?
For a fixed-rate loan refinancing into another fixed-rate loan, the new rate must be at least 0.50 percentage points lower.
If you are moving from a fixed-rate loan into an ARM, the required reduction is at least 2.00 percentage points.
4. What are the actual closing costs?
Ask for the costs in dollars.
Do not stop at phrases such as “no cost,” “no money out of pocket,” or “we’re covering the fees.”
Find out:
- Which costs are being financed into the new loan.
- Which costs are being offset by a lender credit.
- How much your new loan balance will be.
5. How long will it take me to recover those costs?
If your principal-and-interest payment is decreasing, ask to see the recoupment calculation.
The applicable costs must be recovered within 36 months.
You should be able to see the math:
Costs subject to recoupment ÷ monthly P&I savings = months to recoup
6. Am I looking at the payment or the entire refinance?
A lower monthly payment is useful, but it is only part of the decision.
Also compare:
- Your new loan balance.
- Your new interest rate.
- Your closing costs.
- Any lender credits.
- Your new loan term.
- How long you expect to keep the mortgage.
A refinance should improve your overall position, not simply make one number on the page look better.
7. What do I plan to do with the savings?
If the IRRRL lowers your required payment, decide whether you want to:
- Keep the monthly savings and improve cash flow.
- Apply some or all of the savings toward principal.
- Use a combination of both depending on your budget.
A lower required payment gives you flexibility. You can still choose to pay more toward principal when it makes sense.
8. Does restarting a 30-year term fit my goals?
If you have already been in your current mortgage for several years, compare the IRRRL with your remaining payoff schedule.
You may decide that the lower required payment and flexibility of the IRRRL are worth starting a new 30-year term. You may also decide to continue paying extra principal so you do not actually take 30 years to repay it.
If keeping a term closer to your current remaining term is important, compare the IRRRL with a fully underwritten refinance before deciding.
9. Are the lender’s requirements being explained clearly?
Some requirements come directly from VA. Others come from lender or investor guidelines that are commonly used throughout the mortgage industry.
Either way, you should be able to get a clear explanation of what is required, why it is required, and how it affects your loan.
10. Can the lender show me all of this in writing?
This may be the most important question.
You should not have to rely on a phone conversation, a mailer, or someone’s promise that the refinance is a good deal.
Ask to see the numbers.
210 days. Six payments. Required rate reduction. Closing costs. Lender credits. New loan balance. Recoupment period.
If the refinance makes sense, the numbers should be able to prove it.
That is the standard I would use to evaluate an IRRRL from any lender—including me.
VA IRRRL Frequently Asked Questions
Can I use an IRRRL to refinance a conventional, FHA, or USDA loan?
No. A VA IRRRL can only refinance an existing VA-backed mortgage. You cannot use an IRRRL to refinance a conventional, FHA, or USDA loan into a VA loan.
If your current mortgage is not VA-backed, you may still be able to refinance into a VA loan through a fully underwritten VA refinance, but it would not qualify for the streamlined IRRRL process.
Can I get cash back with a VA IRRRL?
No. A VA IRRRL is a rate-and-term refinance, not a cash-out refinance.
You cannot use an IRRRL to borrow against your home equity or receive cash from the loan proceeds. The only cash you may receive at closing is a small incidental refund resulting from an overage or adjustment.
If your goal is to access equity and receive cash back, you would need to consider a VA cash-out refinance instead.
Do I have to live in the home to use an IRRRL?
No. One of the useful differences with a VA IRRRL is that you do not have to currently occupy the property.
For an IRRRL, you generally certify that you currently live in the home or previously lived in it. That means a veteran who bought the property with a VA loan, later moved because of a PCS or other relocation, and now rents the home may still be eligible to refinance that existing VA loan through an IRRRL.
Current occupancy is not required.
Does a VA IRRRL require an appraisal?
Usually, no. VA does not generally require an appraisal for an IRRRL.
That is one of the reasons the program can be more streamlined than a traditional refinance. Since the loan is replacing an existing VA-backed mortgage and does not allow cash out, VA normally does not require a new determination of the property’s value.
A lender may still have its own requirements in certain situations, but a standard VA IRRRL is generally completed without a new appraisal.
Does VA require a minimum credit score for an IRRRL?
No. VA does not establish a minimum credit score for an IRRRL.
However, lenders and investors generally have their own credit standards, and minimum score requirements commonly fall in the 580–640 range.
So a credit-score requirement on an IRRRL may not come directly from VA, but it can still be a legitimate lending requirement that must be satisfied for that lender to close the loan.
What is the VA IRRRL funding fee?
The VA IRRRL funding fee is 0.50% of the new loan amount.
The fee can generally be financed into the new mortgage instead of being paid out of pocket at closing.
Some veterans are exempt from the funding fee, including many veterans receiving VA compensation for a service-connected disability and certain surviving spouses. If you later receive a qualifying disability award with an effective date before your IRRRL closing, a funding fee you already paid may also be refundable.
How long do I have to wait before using an IRRRL?
You generally need to satisfy both VA seasoning requirements before the new IRRRL can close:
- At least 210 days must have passed from the first payment due date on your current VA loan.
- You must have made at least 6 consecutive monthly payments on that loan.
The 210-day clock does not start from your original closing date. It starts from the first payment due date, which is why a veteran can miscalculate eligibility by a month or more if they use the wrong date.
Can I refinance from a 30-year VA loan into a shorter term?
Yes. A VA IRRRL can be used to move into a shorter loan term, but that does not always make it the best structure.
If the shorter term causes your principal-and-interest payment to stay the same or increase, VA’s stricter cost rules apply. In that situation, it may make more sense to compare a fully underwritten refinance—or use the IRRRL to lower the rate and payment, then apply the monthly savings toward extra principal to pay the loan off faster.
Do I need a new Certificate of Eligibility for an IRRRL?
No. You do not need to obtain a new Certificate of Eligibility yourself to complete an IRRRL.
Because an IRRRL is refinancing an existing VA-backed loan, VA already has a record of the entitlement used for that mortgage. If you still have your original COE, you can provide it to the lender. If you do not, the lender can verify your VA eligibility electronically through VA’s system.
So a missing paper COE should not prevent you from exploring an IRRRL.
Can I use a VA IRRRL if I owe more than the home is worth?
Potentially, yes. Because VA generally does not require an appraisal for an IRRRL, a decline in the home’s value does not automatically prevent you from refinancing.
That can make an IRRRL especially useful if you owe more than the property would currently appraise for. The new IRRRL loan amount can be higher than the value of the home, subject to the other IRRRL requirements and the lender’s guidelines.
You still have to meet the normal IRRRL rules, including seasoning, the required rate improvement, and the applicable cost-protection requirements.
Do I have to refinance with my current VA lender?
No. You do not have to use your current lender for a VA IRRRL.
You can refinance with another VA-approved lender, bank, credit union, or mortgage broker as long as the new loan meets VA IRRRL requirements and that lender’s guidelines.
That makes it reasonable to compare offers. Just make sure you are comparing the entire transaction—rate, closing costs, lender credits, new loan balance, and recoupment period—not simply whichever lender advertises the lowest payment.
Does an IRRRL affect my VA loan entitlement?
No. A VA IRRRL reuses the entitlement that is already tied to your existing VA loan. It does not require a new block of entitlement and does not increase the amount of entitlement you already have in use.
In other words, the existing VA loan is being replaced by another VA loan on the same property, so the entitlement simply carries forward with the refinance.
An IRRRL also does not restore that entitlement for use elsewhere. Restoration is a separate issue and generally depends on paying off the prior VA loan and meeting VA’s restoration requirements.
Learn more about how VA entitlements work.
Sources and References
The rules and figures on this page were checked against primary federal and Department of Veterans Affairs sources, rather than relying on lender summaries or third-party mortgage websites.
- 38 U.S.C. § 3709 — Refinancing of Housing Loans
The federal statute governing VA refinance protections, including fee recoupment, net tangible benefit, and loan seasoning requirements. 38 U.S.C. § 3709 - VA Circular 26-19-22 — Clarification and Updates to Policy Guidance for VA IRRRLs
VA guidance explaining the 210-day and six-payment seasoning requirements, rate-reduction standards, fee recoupment, and other IRRRL requirements. VA Circular 26-19-22 - Department of Veterans Affairs — Interest Rate Reduction Refinance Loan (IRRRL)
VA’s official consumer guidance covering IRRRL eligibility, occupancy, Certificate of Eligibility, closing costs, and the basic refinance process. VA IRRRL Guidance - Department of Veterans Affairs — VA Funding Fee and Loan Closing Costs
VA’s current guidance on funding-fee rates, exemptions, financing the fee, and other VA loan closing costs. VA Funding Fee and Closing Costs
Mortgage guidelines and VA policies can change. This page was last reviewed against these sources on August 29, 2026
Want Me to Run the Numbers With You?
If you have an IRRRL offer already—or you simply want to know whether refinancing your current VA loan makes sense—I’m happy to run the numbers with you.
I can show you the proposed rate and payment, closing costs, lender credits, new loan balance, and recoupment period so you can see the entire transaction instead of focusing on one attractive number.
If the refinance makes sense, I’ll show you why. If it doesn’t, I’ll tell you that too.
Buying rather than refinancing? Start here with VA loans.
Call us Directly
Text us for a Quick Response
For a list of our other loan programs, follow this link to our Home Loan Programs page.