

Fort Knox VA Loan Specialists
Your Trusted Local Military Lending Team Serving Radcliff, Elizabethtown, and Vine Grove.
PCSing to Fort Knox? Start Here.
As a retired Army officer who spent more than two decades serving military families, I understand that a PCS move is more than a real estate transaction.
IT'S A MISSION
A mission with a timeline, a family, and dozens of moving parts that must come together successfully.
Whether you’re arriving at Fort Knox for your first assignment, a new duty position, or retirement, our team will help you navigate the homebuying process from initial planning through move-in day.
Use the PCS Housing Checklist below as your guide to a successful Fort Knox relocation.
Nobody Takes Care of Veterans Like a Veteran.
Veteran Owned & Operated
When you call Musketeer Mortgage, you aren’t talking to a corporate call center representative who reads from a script.
YOU ARE TALKING TO FELLOW VETERANS.
Your Fort Knox PCS Housing Checklist
1. Get Prequalified
What to do:
Before you start browsing homes online or scheduling showings, schedule a conversation with us. We’ll review your housing allowance, income, monthly budget, and homeownership goals to determine your buying power and establish a comfortable price range for your home search.
The “Why”:
Military families know the importance of having a plan before execution. Buying a home should be no different. Taking time to establish your budget and buying power before house hunting helps your family focus on homes that fit your goals, avoid unnecessary surprises, and execute a smoother PCS.
2. Lock in Your Pre-Approval
What to do:
Complete your financial readiness packet by providing income, asset, and identification documents. We’ll review everything up front and work toward a fully verified pre-approval so you can begin your home search knowing exactly where you stand financially.
The “Why”:
Service members understand that readiness matters. A fully verified pre-approval ensures your financial documents have already been reviewed and your buying power is clearly established. When the right home appears, you can act decisively instead of scrambling for paperwork, helping your family stay focused on the PCS and not the mortgage process.
3. Begin Your Home Search
What to do:
Begin searching for homes that fit your family’s needs and your approved budget. As you identify properties of interest, keep us involved so we can review estimated payments, taxes, insurance costs, and financing considerations before you make an offer. When you’re ready to submit an offer, we’ll help demonstrate the strength of your financing, answer property-specific financing questions, and communicate directly with the listing agent when needed.
The “Why”:
In a competitive market, sellers want confidence that a transaction will close successfully and on time. A fully verified pre-approval, combined with proactive communication from our team, demonstrates that your financing has already been thoroughly reviewed and positions you as a strong, well-qualified buyer. That confidence can make a meaningful difference when sellers are choosing between multiple offers.
4. Coordinate Your PCS and Closing
What to do:
Once you’re under contract, we’ll coordinate the financing process, appraisal, title work, and closing timeline while helping you align important PCS milestones such as travel dates, reporting requirements, and household goods delivery. Our mission is to help ensure your family can move directly into your new home when you arrive at Fort Knox.
The “Why”:
One of the biggest challenges during a PCS move is ensuring your family, your household goods, and your closing date all arrive at the same destination at the same time. Aligning your closing date with your travel plans, reporting requirements, and household goods delivery helps reduce stress and increases the likelihood that your family can move directly into your new home when you arrive at Fort Knox.
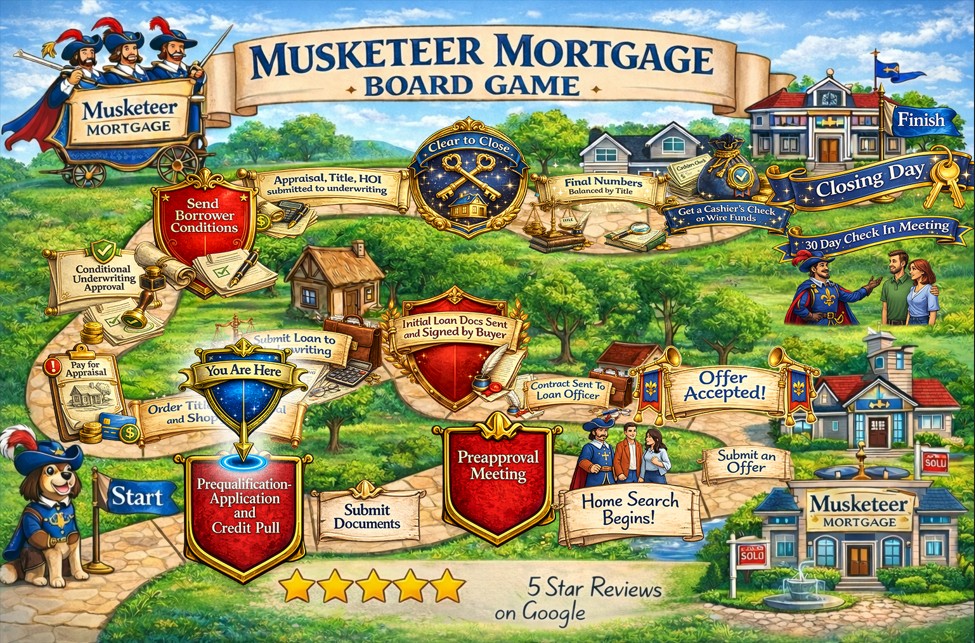
Your Fort Knox VA Loan Roadmap
PCS moves can feel overwhelming. Our goal is to simplify the Fort Knox VA loan process with proactive communication, clear expectations, and guidance from preapproval to closing day.
Frequently Asked Questions
Can I use my VA loan benefit more than once?
Do VA loans require a down payment?
Do VA loans have monthly mortgage insurance (PMI)?
Can I buy a home before I PCS to Fort Knox?
What credit score is needed for a VA loan?
Are VA loans harder for sellers to accept?
What is the VA funding fee and am I exempt?
Can reservists and National Guard members qualify for VA loans?
How fast can you close on a VA loan?
What happens if my PCS orders change during the loan process?
How fast can you clear a pre-approval for a Fort Knox PCS move?
Can I use my basic allowance for housing (BAH) to qualify for a loan?
What if my Statement of Service or orders are delayed by my unit?
Do you offer wholesale loan options outside of standard VA guidelines?
Trusted by Veterans & Military Families Across Kentucky
Our mission is simple: clear communication, honest guidance, and helping military families navigate the home loan process with confidence. Here’s what borrowers have shared about working with Musketeer Mortgage.
“As a military family relocating to Fort Knox, finding the right mortgage team was one of the biggest parts of making our PCS move successful — and Shawn and the Musketeer Mortgage team absolutely exceeded every expectation. Communication was outstanding from start to finish, and they made what could have been a stressful process feel smooth, organized, and genuinely exciting.”
“Because Nevin is a retired veteran and Fort Knox native, his knowledge of the area, the military community, and the PCS process was truly unmatched. He made our move and homebuying experience incredibly smooth, and we’re so grateful we found Nevin and the Musketeer Mortgage team.”
“As a military family relocating to Fort Knox, we needed a mortgage team that truly understood the PCS process, VA loans, and the local area. The Musketeer Mortgage team exceeded every expectation. Their communication was outstanding, they moved quickly, and they made the entire process feel organized and stress-free from start to finish."
The Independent Mortgage Broker
Why Military Families Choose a Local Broker Over Big Retail Lenders & Institutional Banks.
| BENEFIT | MUSKETEER MORTGAGE (BROKER) | BIG RETAIL LENDERS & BANKS |
|---|---|---|
| 1. Rates & Loan Options | ||
| Wholesale Rates | Shop multiple wholesale lenders simultaneously to hunt for the lowest rate. | Stuck with one rigid corporate rate sheet. |
| Loan Comparison | Compare multiple lenders without submitting multiple applications everywhere. | Only offered the products available within one institution. |
| Loan Options | VA, FHA, Conventional, USDA, and Investor programs. | Limited product availability. |
| Flexibility | Ability to pivot lenders if rates, guidelines, or approvals change. | Locked into a single institution’s pricing and underwriting rules. |
| 2. VA Guidelines & Underwriting | ||
| Military Document Fluency | We speak the language fluently. As retired senior leadership, we seamlessly decode complex LES sheets, DD 214s, COEs, and Statements of Service. We have the military background to work directly with units to cut through red tape when a file faces a structural block. | Hourly processing clerks confused by basic military jargon, acronyms, or non-standard income lines, triggering endless paperwork delays. |
| VA Loan Expertise | Deep understanding of VA guidelines, entitlement, and military relocation needs. | Many large lenders treat VA loans like standard conventional loans. |
| Credit Flexibility | Options for complex credit scenarios or low down payment alternatives. | Strict internal minimum scores with high overlays. |
| Problem Solving | Creative solutions for self-employed borrowers, unique income, or credit events. | Difficult scenarios are often declined quickly by automated systems. |
| Underwriting Navigation | Proactive review of potential issues before they become closing delays. | Conditions often generated reactively deep into underwriting. |
| 3. The Closing Experience | ||
| Turnaround Time | Fast processing; clear, direct human updates with no automated hold queues. | Slow corporate bureaucracy and massive call centers. |
| Communication | Direct access to your loan officer and team throughout the process. | Passed between departments and call center representatives. |
| Local Relationships | Strong communication with local agents, title companies, and inspectors. | Transaction coordination often handled remotely with limited local knowledge. |
| Accountability | Your reputation and relationship matter on every file. | Borrowers may feel like just another loan number in a national pipeline. |
| Education | Step-by-step guidance to help borrowers understand the mortgage process. | Limited education and highly transactional interactions. |
| Closing Experience | Hands-on support from application to closing day. | Borrowers often navigate large portions of the process alone. |
| Speed to Adapt | Faster adjustments when contract changes or appraisal issues arise. | Large institutional processes can slow down critical changes. |
| Long-Term Relationship | Ongoing support for future refinancing, purchases, and mortgage planning. | Relationship often ends once the loan closes. |
| Technology + Human Guidance | Modern digital tools combined with real human communication. | Heavy automation with limited personalized guidance. |
| Transparency | Clear explanations of loan structure, costs, and expectations. | Borrowers can feel overwhelmed by automated disclosures and jargon. |
Ready to Turn Your PCS Into a Successful Mission?
Don’t leave your family’s relocation up to automated bank scripts and slow corporate bureaucracy. Let a fellow veteran track your timelines, handle the red tape, and secure the lowest wholesale rate for your Fort Knox home.
Veterans purchasing in the Louisville area can learn more on our Louisville VA Loans page.
Veterans who already own a home here — including those who kept it after a PCS and now rent it out — can learn how to lower the rate on an existing VA loan in our VA IRRRL streamline refinance guide.
Prefer to talk on the phone first?
Call Shawn Neely at 502-310-8405
-or-
Call Nevin Salada at 814-977-0550