

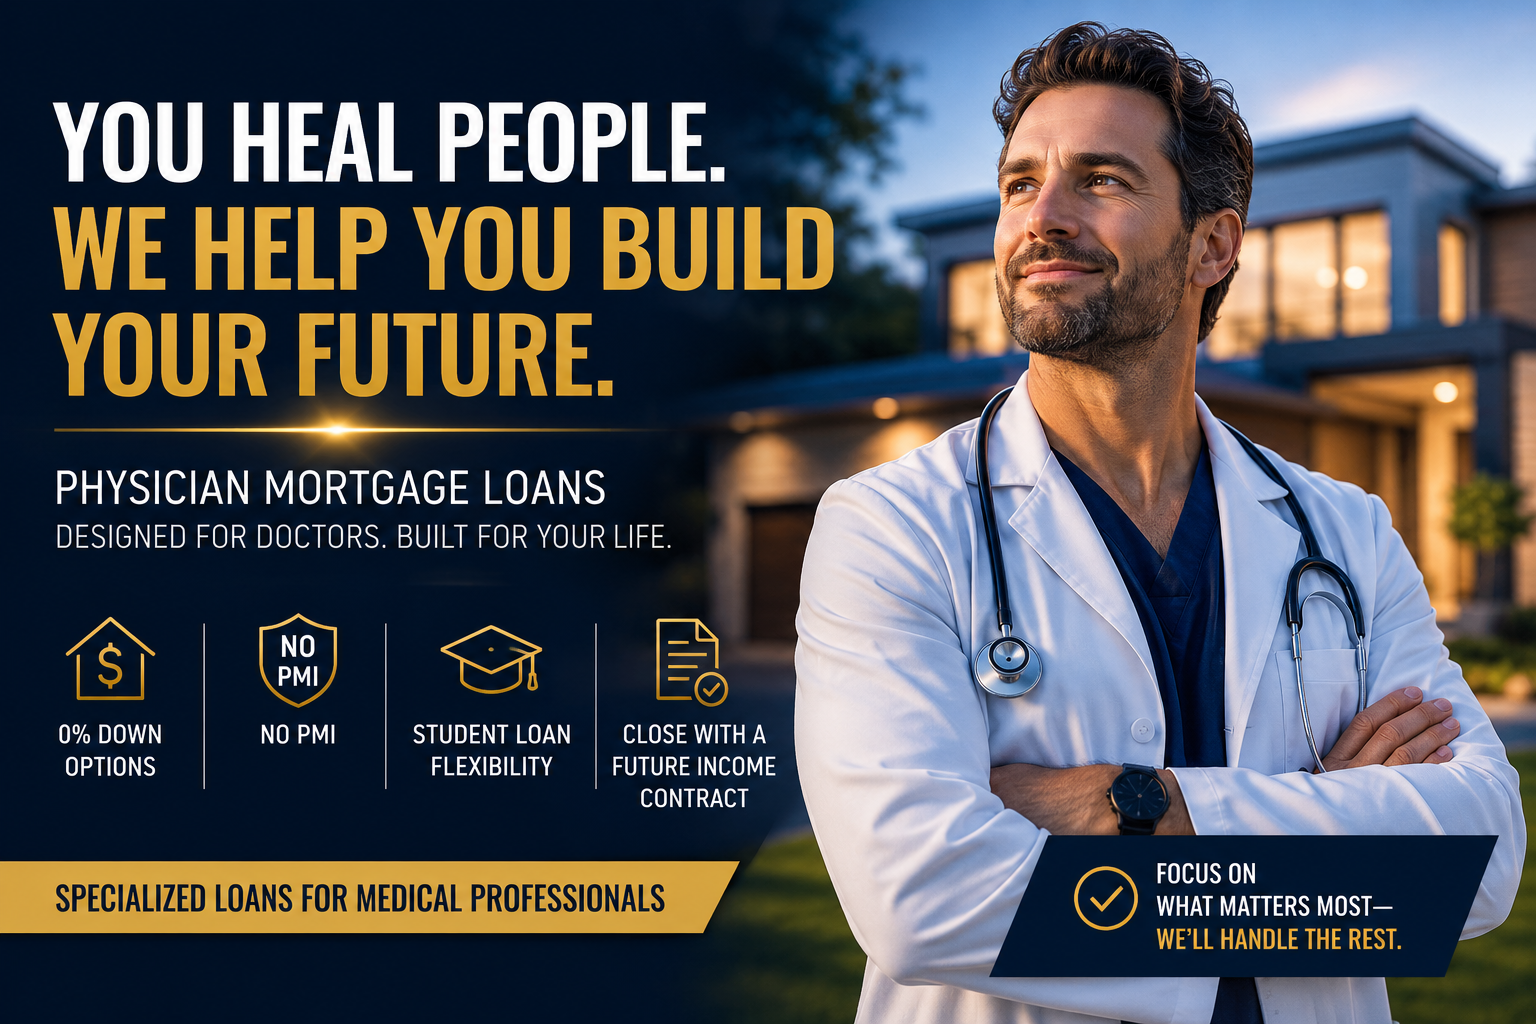
Physician Mortgage Loans for Doctors and Medical Professionals
Buy a home with low or no down payment, no PMI options, flexible student loan treatment, and the ability to qualify using a future employment contract.
Whether you’re beginning residency, completing fellowship training, starting your first attending position, or relocating for a new opportunity, physician mortgage loans are designed around the unique financial realities of medical professionals.
Unlike many traditional mortgage programs, physician loans can offer flexible treatment of student loan debt, low down payment options, and the ability to qualify using future employment income in certain situations.
Explore your options and discover whether a physician mortgage loan may be the right fit for your situation.
│ Eligible Medical Professionals Include: Physicians, Residents, Fellows, Dentists, Veterinarians, Pharmacists, CRNAs, and Other Qualifying Medical Professionals.
Talk With a Mortgage Expert Familiar With Physician Financing
Call us Directly
Text us for a Quick Response
Why Physician Loans Exist
Most doctors and medical professionals follow a very different financial path than the average homebuyer.
After years of education and training, many physicians enter the workforce with significant student loan debt, limited savings, and a new employment contract—even though they may have strong future earning potential.
Common challenges include:
- Significant student loan balances
- Limited funds available for a down payment
- Beginning residency, fellowship, or a new attending position
- Relocating for training or career opportunities
- Strong future income that may not yet appear on tax returns or pay stubs
Traditional mortgage programs don’t always account for these realities. In many cases, highly qualified medical professionals can find themselves facing obstacles despite having excellent career prospects and stable employment.
Physician mortgage loans were created specifically to address these unique circumstances. These specialized programs can provide greater flexibility with student loan debt, lower down payment requirements, and the ability to use future employment contracts in certain situations.
The goal is simple: help qualified medical professionals become homeowners sooner while preserving cash reserves for the transition into their careers.
Physician Loan Benefits
Physician mortgage loans were designed to address the unique financial realities of medical professionals. While program details vary by lender and individual qualifications, these loans may offer advantages that are not commonly available through traditional mortgage programs.
Low or No Down Payment Options
Many physicians begin their careers with strong earning potential but limited cash reserves due to years of education and training. Physician loan programs may allow qualified borrowers to purchase a home with a low down payment—or in some cases, no down payment at all—helping preserve cash for relocation expenses, furnishings, emergency savings, and other financial priorities.
No PMI Options
Traditional mortgage programs often require private mortgage insurance (PMI) when a borrower puts less than 20% down. Certain physician loan programs may waive this requirement for qualified medical professionals, potentially reducing monthly housing costs while allowing you to keep more money available for other goals.
Student Loan Flexibility
Medical school often comes with substantial student loan debt. Physician mortgage programs may offer more flexible treatment of student loan obligations than some traditional mortgage options, helping qualified borrowers maximize purchasing power while accounting for the realities of medical education.
Future Employment Contract Eligibility
Many physicians relocate for residency, fellowship, or their first attending position before receiving a full history of income at their new employer. In certain situations, qualified borrowers may be able to use a signed employment contract to qualify for financing before their first day of work, making it easier to purchase a home during a career transition.
Important: Physician loan programs vary by lender, profession, loan amount, credit profile, and other factors. Not all borrowers or professions will qualify for every benefit. Contact us to discuss your specific situation and available options.
Who May Qualify?
Physician mortgage loan programs are designed for a variety of medical professionals. Eligible professions vary by lender and program, but commonly include:
Physicians & Medical Doctors
✓ Physicians (MD)
✓ Osteopathic Physicians (DO)
Dental Professionals
✓ Dentists (DDS)
✓ Dentists (DMD)
Advanced Medical Professionals
✓ Pharmacists (PharmD)
✓ Podiatrists (DPM)
✓ Certified Registered Nurse Anesthetists (CRNAs) (with DNAP/DNP)
Veterinary Professionals
✓ Veterinarians (DVM)
Medical Training Programs with these degrees
✓ Medical Residents
✓ Fellows
✓ Interns
Why Some Medical Professionals Choose a Physician Loan
While conventional mortgages remain an excellent option for many borrowers, physician mortgage loans were designed to address challenges commonly faced by doctors and medical professionals, including student loan debt, limited savings after years of education, and career transitions associated with residency, fellowship, or new employment opportunities.
Physician Loan vs Conventional Mortgage
| FEATURE | PHYSICIAN LOAN | CONVENTIONAL MORTGAGE |
|---|---|---|
| Down Payment | Low or No Down Payment Options Available | Typically 3%–20% Down |
| PMI | Often Not Required | Usually Required Under 20% Down |
| Student Loan Treatment | More Flexible in Many Cases | Standard Guidelines Apply |
| Future Employment Contract | May Be Accepted | May Be Accepted |
| Cash Reserves | May Preserve More Cash at Closing | Larger Down Payment Often Required |
| Designed For | Medical Professionals | General Borrowers |
Important: Physician loan programs vary by lender, profession, credit profile, loan amount, and other factors. Not all borrowers will qualify for every feature or benefit.
For some medical professionals, a conventional mortgage may still be the better option. An experienced mortgage broker can help you compare both paths and determine which solution best fits your goals.
Buying a Home Before You Start Your New Position
One of the most valuable features of many physician mortgage programs is the ability to purchase a home before your new job officially begins.
This can be especially helpful for medical professionals who are relocating for residency, fellowship training, or a new attending position and need housing before receiving their first paycheck.
Common Situations Where This May Help
- Matching into a residency program in a new city
- Relocating for fellowship training
- Accepting your first attending physician position
- Moving for a new healthcare opportunity
- Purchasing a home before your official start date
In many cases, traditional mortgage programs require a history of income from your new employer before qualifying. Certain physician loan programs may allow qualified borrowers to use a signed employment contract to document future income instead.
Residency Match and Fellowship Relocation
Every year, medical students participate in Match Day and discover where they will complete their residency training.
The challenge is that housing decisions often need to be made quickly.
Waiting until after receiving several paychecks from a new employer may not be practical when you need to relocate across the country and begin training within a few months.
Physician mortgage programs were designed with these realities in mind and may provide financing options that better align with the timelines faced by residents and fellows.
New Attending Physicians
Many newly hired physicians transition from years of training into positions with significantly higher income.
While your future earning potential may be strong, your current financial profile may still reflect years of medical school, residency, and student loan obligations.
Certain physician loan programs recognize this transition and may allow qualified borrowers to leverage a signed employment agreement rather than waiting to establish a lengthy employment history.
Planning Ahead for Your Move
Purchasing a home before your start date can help reduce the stress of relocation and provide stability during a major career transition.
If you’re preparing for residency, fellowship, or a new attending position, we can help you explore available physician loan options and determine whether you may qualify using your employment contract.
Physician Loans for Medical Residents and Fellows
Many medical residents and fellows assume they need to wait until they’ve been on the job for a year—or even longer—before they can qualify for a mortgage.
“I can’t buy a home until I’ve worked for at least a year.”
In many cases, that’s simply not true.
Physician mortgage programs were specifically developed to address the unique career path of medical professionals. Lenders understand that residents and fellows often relocate for training, carry significant student loan debt, and may need housing before receiving their first paycheck from a new employer.Many residents discover where they will be training months before they ever receive their first paycheck. Waiting until after employment begins may not be practical when you need to relocate, secure housing, and begin a demanding new chapter of your career.
Designed Around Medical Career Transitions
Unlike many traditional mortgage programs, certain physician loan options may allow qualified borrowers to use a signed employment contract to document future income rather than requiring an extensive history with their new employer.
This can be particularly helpful when:
- Relocating for residency training
- Beginning a fellowship program
- Transitioning from residency to an attending position
- Moving to a new city for a healthcare opportunity
- Purchasing a home before your official start date
Why This Matters
Medical professionals often face a unique challenge:
You know where you’re going to work.
You know what you’ll be earning.
You have a signed employment agreement.
But you may not have received your first paycheck yet.
Physician mortgage programs were created to help bridge that gap and provide qualified medical professionals with financing solutions that better align with the realities of medical training and career advancement.
Planning for Match Day and Beyond
Every year, medical students participate in Match Day and begin preparing for a move to a new city. Housing is often one of the biggest concerns during this transition.
Rather than waiting until months after starting work, many residents and fellows explore physician mortgage options early so they can understand their financing opportunities and begin planning for a smoother relocation.
If you’re preparing for residency, fellowship, or your first attending position, we can help you explore available physician loan options and determine what may be possible based on your specific situation.
Important: Program guidelines vary by lender, profession, credit profile, loan amount, and other factors. Not all borrowers will qualify, and eligibility requirements differ between programs.
Common Physician Loan Questions
A physician mortgage loan is a specialized home financing program designed for medical professionals. Depending on the program and borrower qualifications, physician loans may offer low or no down payment options, no private mortgage insurance (PMI), flexible student loan treatment, and the ability to qualify using a future employment contract in certain situations.
Eligibility varies by lender and program, but physician mortgage loans are commonly available to:
- Physicians (MD)
- Osteopathic Physicians (DO)
- Dentists (DDS / DMD)
- Veterinarians (DVM)
- Pharmacists (PharmD)
- Podiatrists (DPM)
- CRNAs (with DNAP/DNP)
- Medical Residents
- Fellows
- Interns
Program requirements vary, so it’s important to review your specific situation with a mortgage professional.
In many cases, yes.
Some physician loan programs allow qualified borrowers to use a signed employment contract to document future income before their official start date. This can be especially helpful for residents, fellows, and physicians relocating for a new position.
Many physician mortgage programs do not require private mortgage insurance (PMI), even when putting less than 20% down.
This can significantly reduce monthly housing costs compared to many conventional loan options.
Possibly.
Physician loan programs were created with the understanding that many medical professionals graduate with substantial student loan debt. Some programs offer more flexible treatment of student loans than traditional mortgage programs.
Eligibility depends on the specific loan program and overall financial profile.
Some physician loan programs offer low down payment or even no down payment options for qualified borrowers.
The amount required depends on factors such as:
- Loan amount
- Credit profile
- Occupancy
- Property type
- Individual lender guidelines
No.
Many physician mortgage programs are available to both first-time and experienced homebuyers. Previous homeownership does not automatically disqualify you from a physician loan program.
Yes.
Many physician loan programs were specifically designed around residency and fellowship transitions. Qualified residents and fellows may be able to purchase a home before beginning their new position, depending on the lender’s guidelines.
Not necessarily.
Interest rates vary based on market conditions, credit profile, loan amount, and lender. The overall value of a physician loan often comes from benefits such as lower down payment requirements, reduced cash-to-close needs, flexible student loan treatment, and potential PMI savings.
The best way is to speak with a mortgage professional familiar with physician loan programs.
Because guidelines vary between lenders, a quick review of your profession, employment contract, student loans, credit profile, and homeownership goals can help determine which options may be available.
Yes, in many cases physician mortgage loans can be used more than once.
Medical professionals often relocate throughout their careers for residency, fellowship training, attending positions, hospital transfers, or private practice opportunities. Depending on the lender and your financial qualifications, you may be eligible for another physician loan in the future.
Program guidelines vary, so it’s important to review your current mortgage obligations and homeownership goals with a mortgage professional.
Credit score requirements vary by lender and loan program.
Many physician loan programs require a minimum credit score of 680, while stronger credit profiles may qualify for additional financing options or more favorable terms.
Your credit score is only one part of the approval process. Income, employment history, student loan obligations, reserves, and overall financial strength are also considered.
The best way to determine eligibility is through a personalized mortgage review.
Yes.
Many physicians refinance at some point after purchasing their home. Common reasons include:
- Lowering the interest rate
- Converting an adjustable-rate mortgage (ARM) to a fixed-rate loan
- Removing a co-borrower
- Accessing home equity
- Taking advantage of improved financial qualifications after residency or fellowship
The right refinancing strategy depends on your goals, current loan terms, and market conditions.
Yes, many physician loan programs were specifically designed for medical professionals carrying significant student loan debt.
Unlike some traditional mortgage programs, physician loans may offer more flexible treatment of student loan obligations when determining eligibility. This can help qualified borrowers purchase a home sooner while continuing to manage educational debt.
In many cases, yes. Some physician loan programs are specifically designed for residents and fellows. Program requirements vary by lender and profession, but qualifying may be possible using a signed employment agreement before your start date.
Why Medical Professionals Work With Musketeer Mortgage
Meet Shawn Neely
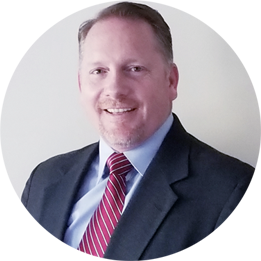
Physician mortgage programs were created to address challenges many medical professionals face when buying a home, including student loan debt, limited savings after years of training, and career transitions associated with residency, fellowship, and new attending positions.
As a retired Army officer, former West Point instructor, and mortgage broker, I’ve built my business around education, communication, and helping clients navigate complex financial decisions with confidence.
Whether you’re beginning residency, relocating for a fellowship, starting a new attending position, or exploring your options as an established medical professional, my goal is simple: provide honest guidance and help you find the mortgage solution that best fits your goals.
Highlights
✓ Retired U.S. Army Officer
✓ Former West Point Instructor
✓ Veteran-Owned Business
✓ Experienced With Complex Income Scenarios
✓ Education Before Sales
Ready to Explore Physician Loan Options?
Every physician’s situation is different. Student loan balances, employment contracts, residency or fellowship status, specialty, income structure, and long-term goals can all influence which mortgage program makes the most sense.
Physician loan programs can offer unique advantages, but not every program is the right fit for every borrower. The best solution depends on your individual circumstances, timeline, and financial objectives.
Whether you’re preparing for residency, relocating for a fellowship, starting your first attending position, or simply exploring your options, we’re here to help you make an informed decision with confidence.
Let’s discuss your goals and determine whether a physician mortgage loan is the right fit for your situation.
Let’s Discuss Your Situation.
Call us Directly
Text us for a Quick Response